RSS

GTA CONDO MARKET SNAPSHOT

July 2026

Market Direction: Sales Stable • Prices Still Below Last Year

The GTA condo apartment market remained relatively stable in July 2026. Sales were almost unchanged from one year ago, while average prices remained below July 2025 levels. Toronto condos performed more strongly than the surrounding 905 market, showing why condo conditions should be analysed locally rather than through one GTA-wide number.


GTA CONDO MARKET AT A GLANCE

Market Indicator

July 2026

YoY Change

Condo Apartment Sales

1,564

-0.1%

Average Selling Price

$636,323

-2.3%

Toronto Condo Sales

1,054

+3.3%

Toronto Avg. Price

$672,807

-1.6%

905 Condo Sales

510

-6.6%

905 Avg. Price

$560,923

-5.0%

TRREB reported 1,564 GTA condo apartment sales in July, with the average selling price at $636,323.


WHAT STANDS OUT

GTA Condo Sales Were Nearly Flat

Condo apartment sales declined only 0.1% year over year, indicating relatively stable transaction activity despite continued price pressure.

Toronto Outperformed the 905

Toronto recorded 1,054 condo sales, up 3.3% year over year.

The 905 recorded 510 sales, down 6.6%.

The difference shows that the GTA condo market is not moving uniformly.

Prices Remain Below Last Year

The average GTA condo price was $636,323, down 2.3%.

Toronto’s average was $672,807, down 1.6%, while the 905 average was $560,923, down 5.0%.


YEAR-TO-DATE CONDO MARKET

Through July 2026:

Market

Sales

Average Price

GTA

9,694

$629,100

Toronto

6,464

$661,770

905

3,230

$563,720

GTA condo apartment sales were up 0.6% year over year YTD, while the average price remained 7.3% lower. Toronto YTD condo sales increased 1.1%, while 905 sales declined 3.8%.


FOR CONDO SELLERS

The July numbers show that buyers are active, but they remain selective.

To compete effectively:

·       Price accurately against current building and neighbourhood competition

·       Review recently sold, active, terminated and relisted units

·       Make presentation and unit condition a priority

·       Highlight parking, locker, floor plan, view, upgrades and building amenities

·       Monitor competing listings throughout the marketing period

Toronto’s stronger sales performance is encouraging, but buyers are still price sensitive.


FOR CONDO BUYERS

July continues to offer buyers negotiating opportunities, especially where listings have been exposed to the market for longer periods.

Buyers should:

·       Compare units within the same building whenever possible

·       Review maintenance fees and included services

·       Examine listing and price-change history

·       Compare parking, locker, exposure, floor level and condition

·       Avoid using the GTA average price as the basis for an individual offer

The 416 and 905 markets are behaving differently, making local analysis particularly important.


BOTTOM LINE

The July 2026 GTA condo market is stable in sales activity but remains price sensitive.

GTA condo sales: Nearly unchanged
Toronto condo sales: Improving
905 condo sales: Softer
Condo prices: Still below last year
Buyer behaviour: Selective and value focused

For sellers, the winning strategy remains accurate pricing, strong presentation and understanding building-level competition.

For buyers, the opportunity comes from identifying which buildings and individual units offer genuine value rather than relying on GTA-wide averages.

GTA Direction. Building-Level Strategy.

Thinking about buying or selling a condo? Request a building and neighbourhood-specific condo market analysis before making your next move.

Source: Toronto Regional Real Estate Board July 2026 Market Watch and July 2026 supporting market data.

🏡 Ready to Start Your Real Estate Journey?
Whether you're planning to buy, sell, or invest, I’m here to guide you every step of the way — surprises and all.

📈 Looking to capitalize on today’s changing market?
Explore a wide range of specialized listings with access to powerful tools and search portals tailored to your needs:

Stay ahead of the curve. Get the latest real estate news and insights right here.


📩 Need help navigating your options?
Reach out for expert advice and market insights:

Sami Chowdhury
BROKER
📧 Email: samichy@torontobase.com
🌐 Web: www.torontobased.com | www.torontobase.ca

Let’s make your next move a smart one.


Get more market insights here:

Stay ahead of the curve. Get the latest real estate news and insights right here.


Read

GTA Housing Market July 2026: Why Falling Inventory Is Changing the Market

The Greater Toronto Area housing market entered July 2026 with a contradiction that deserves more attention than the headline numbers alone suggest.

Prices were still below last year’s levels. Homes were still taking longer to sell. Buyers were still negotiating. Yet at the same time, the supply of homes coming onto the market dropped sharply, active inventory declined, year-to-date sales moved slightly ahead of last year, and seasonally adjusted sales improved from June.

That combination makes July one of the more important transition months of 2026.

The GTA did not suddenly become a strong seller’s market. There is no evidence in the July data of a broad price surge or widespread bidding-war environment. But the conditions that gave buyers significant leverage are starting to change.

GTA REALTORS® reported 5,995 sales in July 2026, only 0.9% below the 6,047 sales recorded in July 2025. At the same time, new listings dropped 17.8% year over year, falling from 17,623 to 14,484. Active listings declined 12.1% to 26,098. The average selling price was $1,003,956, down 4.5% from July 2025, while the MLS® Home Price Index Composite benchmark remained approximately 4.6% lower year over year.

The most important number may therefore not be the 0.9% sales decline or even the 4.5% price decline.

It is the 17.8% reduction in new listings.

Demand has remained relatively stable while supply has contracted much faster.

If that pattern continues, the market buyers face later this year could look very different from the one they experienced during periods of expanding inventory.

For sellers, that does not mean it is time to raise the asking price simply because competition is declining.

For buyers, it does not mean opportunity has disappeared.

For investors, it does not mean every discounted property suddenly represents value.

July’s market rewards something more useful than optimism or pessimism: careful interpretation of the numbers, local market analysis, accurate pricing and disciplined decision making.


The July 2026 GTA Housing Market at a Glance

The primary GTA numbers for July were:

Metric

July 2026

July 2025

Change

Sales

5,995

6,047

-0.9%

New Listings

14,484

17,623

-17.8%

Active Listings

26,098

29,707

-12.1%

Average Price

$1,003,956

$1,051,600

-4.5%

Avg. LDOM

32 days

30 days

+6.7%

Avg. PDOM

45 days

40 days

+12.5%

TRREB’s July Market Watch also reports a GTA dashboard average sale-price-to-list-price ratio of approximately 97.3%.

Those numbers describe a market that is still price sensitive but becoming tighter.

The distinction is important.

A market can tighten without prices immediately rising. Supply and demand conditions generally have to change before the resulting effect becomes fully visible in transaction prices.

July may be showing that first part of the process.


The Biggest July Story: Supply Fell Much Faster Than Sales

A homeowner reading that sales were down 0.9% might assume the market weakened again.

A buyer reading that the average price was down 4.5% might reach the same conclusion.

Neither interpretation captures the full picture.

Consider what happened to supply.

Sales moved from 6,047 to 5,995, a difference of just 52 transactions.

New listings, however, dropped from 17,623 to 14,484.

That is 3,139 fewer new listings coming onto the market than one year earlier.

Active inventory also fell from 29,707 to 26,098.

This is why the relationship between sales and listings matters more than either number in isolation.

When sales fall slightly but new supply falls dramatically, buyers have fewer new options entering the market relative to the number of transactions taking place.

TRREB explicitly characterized July conditions as tighter and noted that active buyers were facing more competition from other purchasers because listings had declined substantially.

That does not automatically create price growth.

What it does is reduce one of the conditions that normally supports falling prices: continuously expanding choice.

When buyers can choose among a large and growing number of comparable properties, they can reject an overpriced listing and move to the next one.

When competing inventory begins shrinking, that strategy becomes less reliable.

A good property priced properly can attract attention faster because buyers have fewer substitutes.

This is where the July market begins to look different.


Month-to-Month Momentum Also Tightened

The year-over-year comparison is only one part of the story.

TRREB’s seasonally adjusted data gives us another useful perspective because it helps identify the underlying month-to-month direction.

From June to July 2026:

·       Seasonally adjusted sales increased 3.2%

·       Seasonally adjusted new listings declined 1.5%

·       Seasonally adjusted average price declined 0.6%

·       MLS® HPI increased 0.3%

The seasonally adjusted sales total increased from 5,411 in June to 5,582 in July, while new listings declined from 12,926 to 12,730. The HPI moved from $931,100 to $933,800.

This creates an interesting sequence.

Transaction activity improved.

New supply declined.

The benchmark price edged higher.

Yet the seasonally adjusted average price moved slightly lower.

That is exactly why one month should not be reduced to a single number.

Average price can move because of the mix of homes sold. The HPI is designed to track price movement differently. When they move in slightly different directions during a transition period, the safest interpretation is not that prices are surging or collapsing.

The stronger conclusion is that underlying market conditions tightened while price stabilization remained incomplete.


Prices Are Still Below Last Year

There is no reason to minimize the price correction.

The July average selling price of $1,003,956 was 4.5% below July 2025.

The MLS® HPI Composite benchmark was down approximately 4.6%.

Those two measurements pointing in a similar direction strengthen the evidence that values remained below year-ago levels.

The market has therefore not erased the price adjustment experienced by homeowners.

But the direction of supply matters because prices do not move independently of market balance.

A market can remain below last year’s price level while moving closer to stabilization.

That is a more accurate description of July.

TRREB itself suggested that if current tightening trends continue, average selling prices could begin to level off in the second half of the year. That is a conditional statement, not a guarantee, and it should be treated that way.

The word if matters.

If listings begin increasing significantly again, the balance could shift back.

If sales weaken materially, tighter supply might not be enough to support prices.

If buyers remain cautious because of economic or borrowing concerns, homes can continue taking time to sell even with fewer listings entering the market.

July has changed the setup.

It has not predetermined the outcome.


Year-to-Date Numbers Reveal Another Important Shift

Looking only at July can hide a larger trend.

Through the first seven months of 2026, the GTA recorded:

·       37,105 sales

·       $1,032,207 average selling price

·       102,566 new listings

For the comparable period in 2025:

·       Sales were 36,891

·       Average price was $1,087,954

·       New listings were 120,911

That means year-to-date sales were approximately 0.6% higher, while the average price remained approximately 5.1% lower and new listings were approximately 15.2% lower.

The relationship is revealing.

The number of transactions has effectively stabilized relative to last year.

Prices remain lower.

The flow of new supply has contracted considerably.

This suggests the adjustment in 2026 is not simply a story of disappearing buyers.

There are buyers.

They are purchasing.

What has changed is the price at which many of those transactions are occurring and the amount of inventory competing for their attention.

For real estate clients, this distinction can be more useful than declaring that the market is simply “up” or “down.”


Detached Homes: Sales Stabilized Before Prices

Detached homes accounted for the largest share of July GTA sales.

There were 2,789 detached transactions, representing approximately 46.5% of all sales in the Market Watch price-range table.

The GTA detached average price was $1,291,690.

Compared with July 2025:

·       Detached sales increased 0.6%

·       Detached average price declined 5.1%

That is a classic example of activity stabilizing before pricing fully follows.

The 416 and 905 markets also behaved differently.

City of Toronto detached

·       Sales: 691

·       Average price: $1,547,928

·       Sales change: +2.8%

·       Price change: -1.5%

905 detached

·       Sales: 2,098

·       Average price: $1,207,295

·       Sales change: -0.1%

·       Price change: -6.7%

The same property category therefore produced very different results depending on geography.

For a seller, that is a reminder that a GTA detached average is not a pricing strategy.

For a buyer, it is evidence that negotiation expectations should be based on the local market rather than on a regional headline.


Semi-Detached Homes Faced Greater Price Pressure

Semi-detached properties recorded:

·       557 GTA sales

·       $964,922 average price

·       Sales change: -5.9%

·       Price change: -7.4%

Among the four major housing types reported by TRREB, this was the largest GTA average-price decline in July.

The Toronto and 905 split again matters.

Toronto’s semi-detached average was $1,122,326, while the 905 average was $851,726.

Sales were down 6.8% in the 416 and 5.3% in the 905.

Prices declined 9.9% in Toronto and 4.6% in the 905.

A homeowner looking at the GTA average alone could miss substantial differences between locations.


Townhouses Continue to Fill an Important Middle Ground

TRREB reported 1,003 townhouse sales in July.

The GTA average price was $817,213.

Compared with July 2025:

·       Sales declined 2.7%

·       Average price declined 3.9%

Toronto townhouse sales increased 8.7%, while 905 sales declined 6.0%.

Toronto’s average townhouse price was $867,635, compared with $800,561 in the 905.

That divergence in sales activity again demonstrates why broad market labels can mislead.

For buyers moving between property types, townhouses may sit between condominium apartments and detached ownership from a pricing perspective, but they should still be analysed as their own market segment.


Condominiums: Stable Sales Do Not Mean the Same Market Everywhere

The GTA recorded 1,564 condo apartment sales during July.

The average price was $636,323.

Sales were almost unchanged from one year earlier, declining only 0.1%, while the average price declined 2.3%.

But there was a notable geographical split.

Toronto condo apartments

·       Sales: 1,054

·       Sales change: +3.3%

·       Average price: $672,807

·       Price change: -1.6%

905 condo apartments

·       Sales: 510

·       Sales change: -6.6%

·       Average price: $560,923

·       Price change: -5.0%

The GTA-wide condo number therefore hides two different patterns.

Toronto condo transaction activity improved year over year while the 905 condo segment experienced weaker sales and greater price pressure.

For condo sellers, building-level competition, maintenance fees, layout, parking, condition and local inventory can matter enormously.

For buyers, the same creates opportunity to be selective rather than assuming every condominium is equally negotiable.


Toronto and the Rest of the GTA Are Moving Differently

The official July comparison separates the City of Toronto from the rest of the GTA.

City of Toronto

·       Sales: 2,242

·       Average price: $1,010,836

·       New listings: 4,980

July 2025:

·       Sales: 2,190

·       Average price: $1,045,159

·       New listings: 6,013

Toronto sales therefore increased while new listings dropped substantially.

Rest of GTA

·       Sales: 3,753

·       Average price: $999,845

·       New listings: 9,504

July 2025:

·       Sales: 3,857

·       Average price: $1,055,258

·       New listings: 11,610

The rest of the GTA experienced lower sales and lower prices, but it also experienced a substantial reduction in new listings.

This reinforces the central July theme: the supply contraction is broad enough to matter, even where sales have not strengthened.


Regional Conditions Are Far From Uniform

The monthly regional dashboard provides another layer of detail.

Toronto

·       Sales: 2,242

·       Average price: $1,010,836

·       New listings: 4,980

·       Active listings: 9,310

·       Average MOI: 4.2

·       Average SP/LP: 97.3%

Halton

·       Sales: 682

·       Average price: $1,151,595

·       New listings: 1,503

·       Active listings: 2,659

·       Average MOI: 3.9

·       Average SP/LP: 96.2%

Peel

·       Sales: 1,053

·       Average price: $910,007

·       New listings: 2,875

·       Active listings: 5,055

·       Average MOI: 4.8

·       Average SP/LP: 97.2%

York

·       Sales: 1,063

·       Average price: $1,146,307

·       New listings: 2,764

·       Active listings: 5,179

·       Average MOI: 4.9

·       Average SP/LP: 97.6%

Durham

·       Sales: 725

·       Average price: $834,312

·       New listings: 1,719

·       Active listings: 2,579

·       Average MOI: 3.6

·       Average SP/LP: 98.4%

Simcoe

·       Sales: 194

·       Average price: $821,174

·       New listings: 554

·       Active listings: 1,159

·       Average MOI: 6.0

·       Average SP/LP: 96.2%

These numbers demonstrate why clients need local advice.

Durham, with 3.6 months of inventory and a 98.4% sale-price-to-list-price ratio, was behaving differently from Simcoe, where the dashboard showed 6.0 months of inventory and a 96.2% ratio.

A negotiation strategy that is effective in one region may be inappropriate in another.

And even these regional figures remain broad averages. Individual municipalities and neighbourhoods can behave differently again.


Days on Market Tell Us Buyers Are Still Selective

One of the reasons it would be premature to describe July as a strong seller’s market is the time properties are taking to sell.

Across all TRREB areas:

·       July average LDOM: 32 days

·       July average PDOM: 45 days

·       YTD average LDOM: 31 days

·       YTD average PDOM: 46 days

TRREB defines LDOM as the number of days sold listings were on the market. PDOM represents the time a property was on the market before selling regardless of whether it was listed more than once by the same seller and brokerage combination during the original listing contract period.

The July Days on Market comparison confirms that the gap varies widely by municipality.

This distinction matters for sellers.

A listing may appear relatively fresh after being cancelled and relisted, but buyers and agents can often evaluate the property’s broader exposure history.

It also matters when setting expectations.

A seller should not interpret tighter inventory as a guarantee of an immediate sale.

The average property can still require patience, proper positioning and, in some cases, a strategy adjustment.


The 97.3% Sale-to-List Ratio Has a Practical Meaning

The GTA dashboard showed an average SP/LP ratio of approximately 97.3%.

That tells us something about buyer behaviour.

At the market-wide level, the typical transaction is not simply closing at the asking price.

Negotiation remains part of the market.

But this figure should not be turned into a rule such as “offer 2.7% below asking.”

That would misuse an average.

Some properties are deliberately listed below expected market value.

Others are priced aggressively and require reductions.

Some sell above asking.

Others sell substantially below.

The better use of SP/LP data is as evidence that asking price and market value are not the same thing.

Buyers should analyse comparable sales and listing history rather than mechanically applying a discount.

Sellers should understand that buyers are comparing value carefully and will punish an unrealistic asking price.


Buyer Strategy for the July 2026 Market

For buyers, July creates an unusual combination of opportunity and risk.

Prices remain below last year, which can improve purchasing opportunities relative to previous price levels.

But inventory is beginning to contract.

That means the buyer who waits simply because they expect more and more selection may be making an assumption that the July data no longer supports.

1. Do not confuse lower prices with unlimited negotiating power

The GTA average price is down, but new listings are falling much faster than sales.

A stale listing that has been sitting for weeks may still offer negotiating opportunity.

A newly listed, well-positioned property in a desirable area may not.

Treat each property independently.

2. Watch competing inventory

Before making an offer, ask:

·       How many similar homes are currently active?

·       How long have they been listed?

·       Have comparable listings terminated or been relisted?

·       How many comparable homes recently sold?

·       Is new inventory increasing or declining in this specific neighbourhood?

The GTA trend tells us supply is tightening.

The neighbourhood tells us whether that trend applies to the property you actually want.

3. Separate asking price from value

The 97.3% GTA SP/LP ratio shows negotiation exists, but it does not tell you what any individual property is worth.

Use sold comparables.

Look at condition, lot, renovation quality, parking, location and property type.

An overpriced listing may deserve a substantial discount.

A correctly priced listing may not.

4. Have financing ready before competition increases

The supplied TRREB Market Watch lists the July Bank of Canada overnight rate at 2.3%, prime rate at 4.5%, and posted mortgage rates in the report of 5.49% for one year, 6.05% for three years and 6.09% for five years.

Those are the figures supplied in this dataset and should not be interpreted as a personalized mortgage quote.

The strategic point is simpler: financing affects purchasing power, so buyers should understand their own qualification before becoming emotionally committed to a property.

5. Do not wait for a perfect market

A perfect buying market rarely announces itself.

The best time for an individual buyer depends on affordability, financing, job stability, planned ownership period, property quality and price.

July suggests that buyers still have leverage, but that leverage may become less broad if inventory continues contracting.


Seller Strategy for the July 2026 Market

Sellers have more encouraging information in July than they had from price statistics alone.

But execution still matters.

1. Fewer listings mean fewer competitors

A 17.8% year-over-year decline in new listings is significant.

If your neighbourhood is experiencing the same pattern, there may be fewer comparable homes competing for buyer attention.

That can improve the visibility of a strong listing.

2. Do not price as though the correction never happened

The GTA average price remains 4.5% below last year.

Major housing categories remain below last year’s average prices.

Buyers know this.

A seller who anchors to a previous market peak or an outdated comparable risks becoming part of the stale inventory buyers use to negotiate against.

3. The first days still matter

When there are fewer new listings, buyers may pay more attention to a well-presented new property.

That makes launch strategy important:

·       accurate price

·       strong photography

·       proper preparation

·       complete property information

·       convenient showing access

·       effective online exposure

·       rapid follow-up

The objective is not merely to list.

It is to capture the greatest possible share of active buyer attention while the property is fresh.

4. Monitor reaction, not just traffic

Showings alone do not prove the price is correct.

Seller strategy should monitor:

·       showing volume

·       second showings

·       buyer questions

·       agent feedback

·       competing listings

·       new comparable sales

·       offers

·       objections

If buyers repeatedly view the home but choose alternatives, the market may be providing a pricing or presentation signal.

5. Tighter supply may improve negotiating position

TRREB specifically noted that buyers could find less room to negotiate if sales continue to account for a larger share of available listings.

That possibility is important.

But sellers should earn stronger negotiating leverage through accurate positioning rather than assuming it exists automatically.


What the July Market Means for Investors

The July resale numbers can help investors understand market direction, but they do not answer the most important investment questions by themselves.

The supplied dataset does not provide:

·       rental rates

·       vacancy rates

·       cap rates

·       property operating expenses

·       condominium maintenance costs for individual units

·       financing costs for individual borrowers

·       cash-flow projections

·       renovation costs

Those metrics cannot be invented.

What July does show is that resale values remain below year-ago levels while sales activity is stabilizing and supply is contracting.

That can create a more interesting acquisition environment for an investor who already has a sound property-level analysis.

For example, an investor may find a property selling below a comparable value from one year ago.

That does not automatically make it a good investment.

The relevant question is:

What return does this property produce at today’s acquisition price and my actual cost structure?

An investor should therefore evaluate:

1.       Purchase price

2.       Financing

3.       Rental income

4.       Property taxes

5.       Maintenance

6.       Insurance

7.       Vacancy allowance

8.       Repairs

9.       Condominium fees where applicable

10.  Expected holding period

11.  Exit strategy

The July TRREB data provides market context.

It does not replace investment underwriting.


Buyer and Seller Psychology May Be the Next Major Variable

Markets are not driven by numbers alone.

People respond to what they believe the numbers mean.

TRREB noted that many would-be buyers continue to wait for greater confidence around the economy, inflation, borrowing costs and related uncertainty. The July report also said recent economic and employment readings had been more positive than expected and suggested stronger confidence could eventually support additional purchasing activity.

The supplied economic indicators show why caution can coexist with opportunity.

TRREB’s July Market Watch lists:

·       Q1 real GDP growth: -0.1%

·       Toronto employment growth in June: +0.9%

·       Toronto unemployment rate in June: 7.2%

·       June inflation: 2.8%

·       Bank of Canada overnight rate in July: 2.3%

·       Prime rate: 4.5%

These numbers describe an environment where buyers can reasonably remain cautious even as market conditions tighten.

Psychology becomes important because a change in confidence can affect demand faster than housing supply can respond.

If hesitant buyers return while listing supply remains constrained, competition could strengthen.

If confidence deteriorates instead, buyers may remain patient despite lower inventory.

That is one of the key uncertainties heading toward the fall market.


Three Risk Scenarios for the Next Stage of the GTA Market

The July data supports several possible paths. It does not allow a precise forecast, but it does allow us to identify the variables that matter.

Scenario 1: Supply continues falling while demand remains stable

This is the continuation of July’s pattern.

Sales do not need to surge.

If sales remain relatively steady while new and active inventory contract, buyers have fewer alternatives.

That could reduce negotiating leverage and improve the probability of price stabilization.

This is the scenario closest to TRREB’s July interpretation.


Scenario 2: Fall listings return strongly

July may represent a temporary period of limited new supply.

If a large number of sellers enter the market later, buyers could regain more choice.

That would make pricing and presentation even more important.

The July dataset does not provide future listing totals, so this scenario cannot be assigned a probability from the information supplied.


Scenario 3: Buyer confidence weakens

Even limited inventory does not guarantee price strength.

If economic concerns, employment conditions or borrowing costs cause purchasers to step back materially, fewer listings could be matched by fewer willing buyers.

The result could be slower sales and continued price pressure.

Again, the dataset does not forecast this outcome.

It simply identifies the factors TRREB itself highlighted as important to purchaser confidence.


What Could Cause Prices to Stabilize?

For prices to become more stable, the relationship between willing buyers and available homes must become more balanced.

July moved in that direction.

Sales were almost unchanged year over year.

New listings fell sharply.

Active inventory declined.

Seasonally adjusted sales increased.

Seasonally adjusted new listings declined.

The seasonally adjusted HPI edged higher.

Those are constructive ingredients.

But two other pieces of evidence remain important:

Average prices were still below last year.

Days on market remained longer.

This is why July should be interpreted as an early stabilization phase, not a confirmed recovery.

A stabilization phase can last.

It can reverse.

It can also develop into a stronger market if demand continues improving relative to supply.

The next several months will show whether July was the beginning of a durable change or simply one stage in a longer adjustment.


The Most Important Advice for Buyers: Localize the Data

A GTA average is useful for understanding direction.

It is not enough to decide what to offer on a home.

A buyer looking in Durham, for example, is operating in different conditions from someone looking in York or Simcoe.

Even within Toronto, Central, East and West districts have different sales volumes, prices, days on market and listing conditions.

The same is true from one neighbourhood to another.

Before making an offer, the most useful analysis is therefore not:

“What is the GTA doing?”

It is:

“What are comparable homes in this immediate market doing right now?”

That requires current listings, recent sold properties, listing history, days on market and the condition of the specific property.


The Most Important Advice for Sellers: Price for the Market You Have

Sellers can make the opposite mistake.

They see declining inventory and immediately conclude prices should rise.

But buyers do not purchase a supply statistic.

They purchase a property at a price they believe represents value.

A seller’s goal is to position the home where the available demand is most likely to respond.

That means comparing the property with what buyers can purchase today, not simply with what a neighbour sold for in a different market.

The July numbers offer sellers a potentially improving backdrop.

They do not replace proper pricing.

In a transitioning market, the seller who recognizes changing conditions early can benefit.

The seller who gets too far ahead of the market can still sit unsold.


The Fall Market Could Become More Competitive Without Becoming a Boom

This is perhaps the most useful way to frame July.

The GTA does not need a dramatic increase in sales for buyers to experience more competition.

Competition can increase simply because there are fewer properties available relative to the number of active buyers.

That is what the July numbers are beginning to show.

If sales remain stable and listings continue declining, well-priced homes may attract stronger attention.

Properties with major deficiencies or unrealistic prices may still struggle.

That would create an increasingly divided market:

good property + good price + good presentation = stronger response

while:

poor positioning + unrealistic price = continued resistance

This is not contradictory.

It is exactly what can happen when a market transitions from widespread buyer leverage toward more balanced conditions.


July 2026 Is Not One Market

Perhaps the biggest mistake consumers make is assuming the GTA market has one temperature.

It does not.

Toronto is different from York.

York is different from Durham.

Durham is different from Simcoe.

Detached homes are different from condos.

A renovated home is different from one requiring significant work.

A property listed accurately is different from one priced on seller expectations.

A condominium with heavy competing inventory can behave differently from another building a few streets away.

That means one number can never answer the question buyers and sellers actually care about:

What does this market mean for me?

July’s GTA numbers provide the direction.

The answer for an individual client requires local analysis.


What Comes Next

The July 2026 TRREB data points to a market that is changing underneath the headline price numbers.

Sales are no longer falling significantly year over year.

Year-to-date sales have edged slightly ahead of last year.

New listings have contracted sharply.

Active inventory is lower.

Seasonally adjusted sales strengthened in July while new listings declined.

Prices, however, remain below last year’s levels, and properties continue to require more time to sell than they did one year ago.

That combination is best understood as supply-led tightening with early signs of price stabilization.

For buyers, the message is not to panic or rush.

It is to recognize that the period of continuously expanding choice may not continue indefinitely.

For sellers, the message is not to overprice.

It is to recognize that reduced competition can become an advantage when the home is positioned properly.

For investors, the message is to separate market direction from property economics.

The resale market may be stabilizing, but investment quality still depends on the individual numbers of the property.

The next stage of the GTA market will depend heavily on whether sales remain resilient and whether homeowners continue holding back new supply.

If that happens, buyer negotiating power could narrow and price stability could become more visible.

If listings return strongly or buyer confidence weakens, the market could remain softer for longer.

The July numbers do not justify certainty in either direction.

They do justify paying closer attention.

Thinking About Buying or Selling in the GTA?

GTA-wide statistics are the starting point, not the answer.

Your neighbourhood, property type, price range and competing inventory can behave very differently from the regional average.

If you are considering selling, I can prepare a property-specific market analysis showing the recent sales, current competition, pricing trends and buyer activity affecting your home.

If you are buying, I can prepare a neighbourhood-specific buyer analysis to show where inventory, pricing and negotiating conditions may be creating opportunities.

Contact me for a current neighbourhood and property-specific market analysis before making your next move.

Market data used in this report is drawn exclusively from the supplied Toronto Regional Real Estate Board July 2026 Market Watch, official TRREB July news release, regional dashboards and Days on Market comparison. Market-wide statistics should not be interpreted as a valuation of an individual property.

🏡 Ready to Start Your Real Estate Journey?
Whether you're planning to buy, sell, or invest, I’m here to guide you every step of the way — surprises and all.

📈 Looking to capitalize on today’s changing market?
Explore a wide range of specialized listings with access to powerful tools and search portals tailored to your needs:

Stay ahead of the curve. Get the latest real estate news and insights right here.


📩 Need help navigating your options?
Reach out for expert advice and market insights:

Sami Chowdhury
BROKER
📧 Email: samichy@torontobase.com
🌐 Web: www.torontobased.com | www.torontobase.ca

Let’s make your next move a smart one.


Get more market insights here:

Stay ahead of the curve. Get the latest real estate news and insights right here.


Read

Greater Toronto Area Housing Market Report

June 2026

Market Conditions Improve as Sales Rise and Available Inventory Declines

The Greater Toronto Area housing market showed a meaningful improvement in June 2026. Sales activity increased compared with the same month last year, fewer new properties entered the market, and the total number of active listings declined.

These changes indicate that demand strengthened while supply tightened. This represents a significant shift from the conditions experienced earlier in 2026, when cautious buyers and elevated inventory placed greater pressure on sellers.

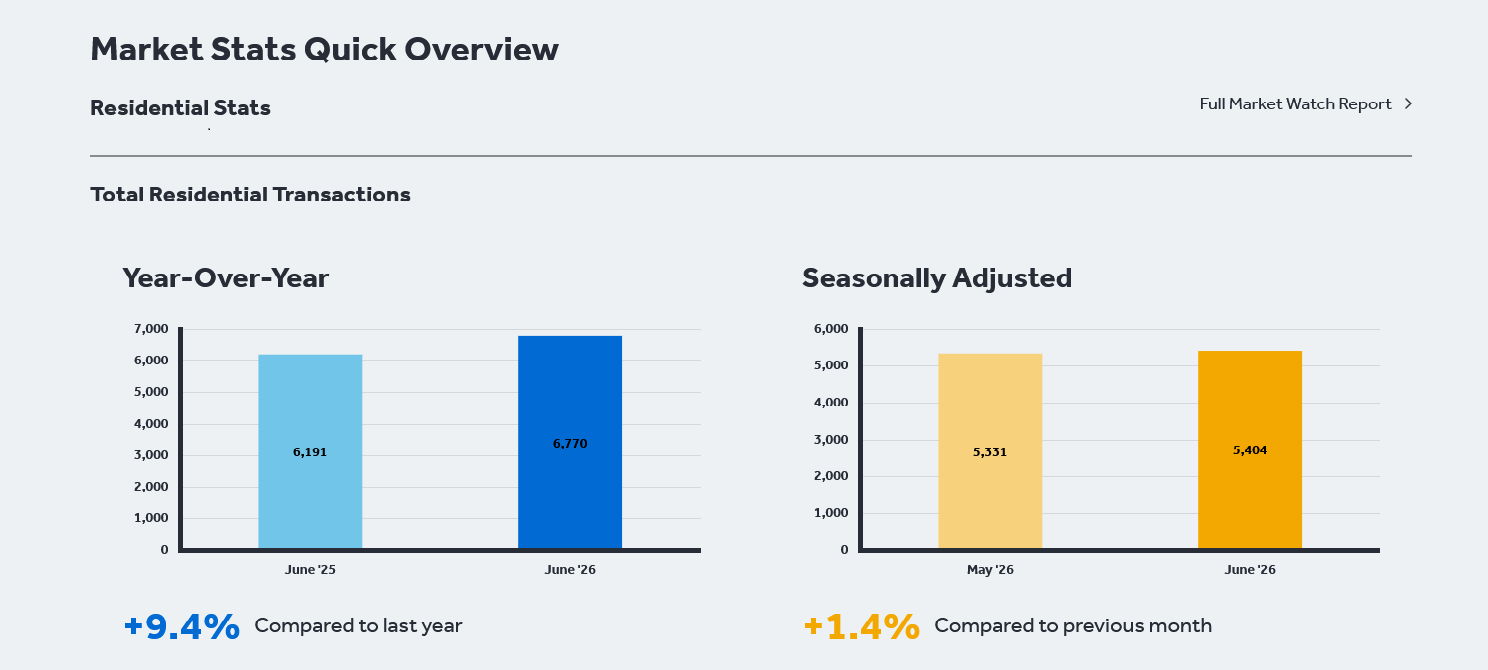
A total of 6,770 homes were sold through the TRREB MLS® System in June 2026. This was an increase of 9.4 per cent compared with the 6,191 sales recorded in June 2025.

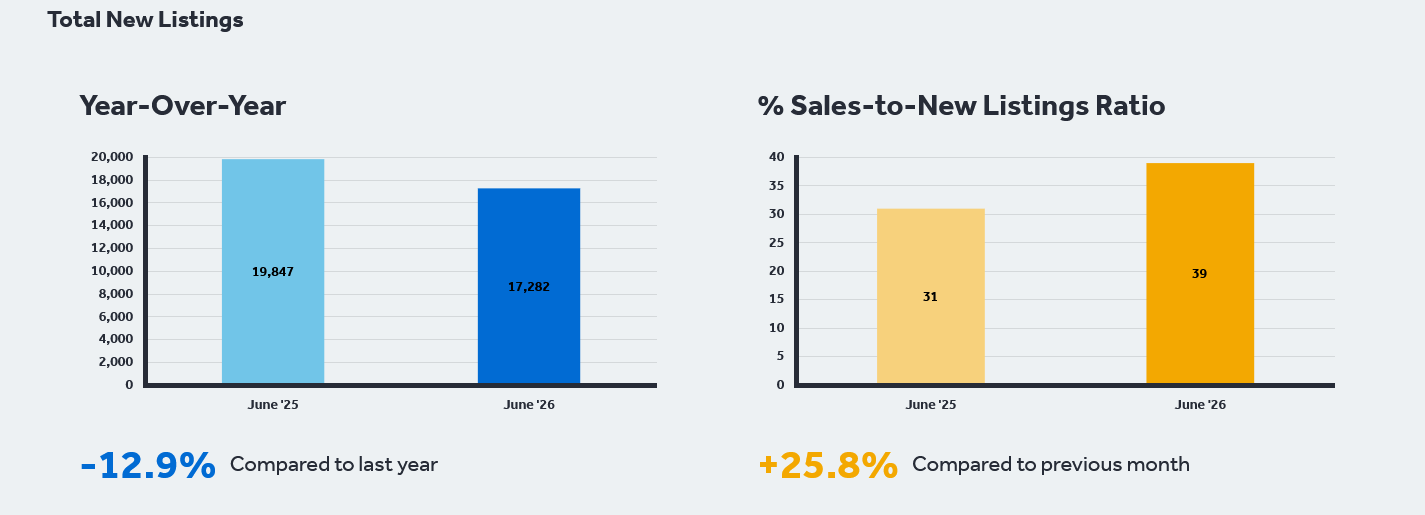
New listings moved in the opposite direction. A total of 17,282 new listings entered the market, down 12.9 per cent from 19,847 one year earlier. Active listings also declined, falling 13.5 per cent from 31,585 in June 2025 to 27,329 in June 2026.

The combination of rising sales and declining inventory is the most important development in the June report. It shows that buyers are returning to the market at the same time that the available supply of homes is being reduced.

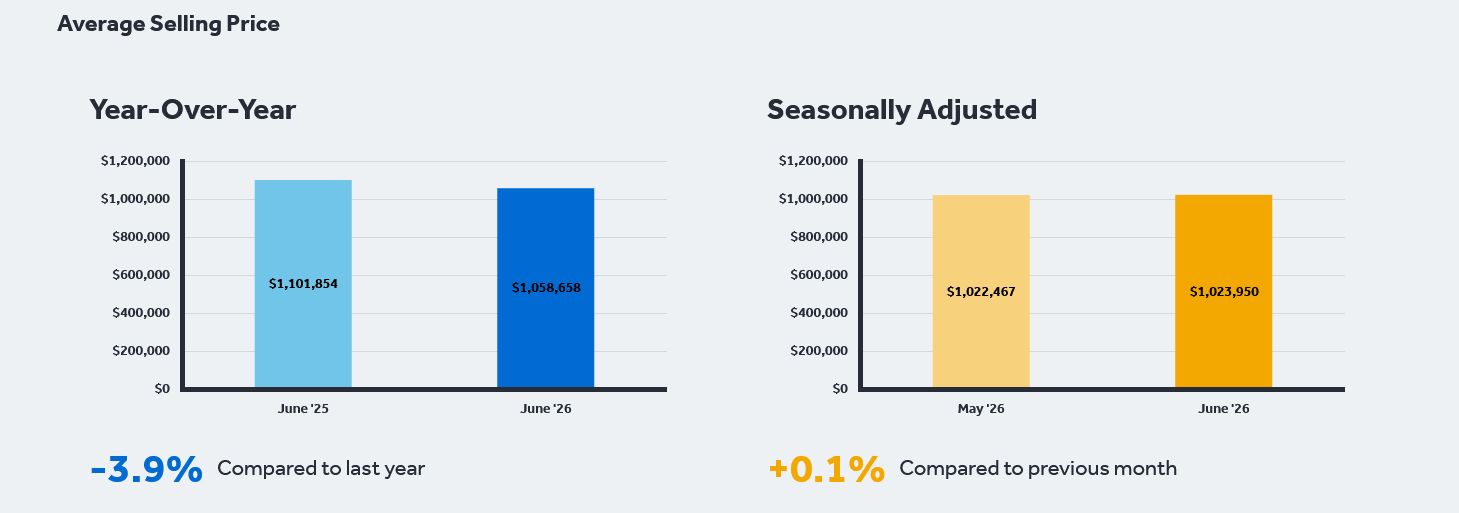
Prices remained below last year’s levels, however. The average GTA selling price was $1,058,658, down 3.9 per cent from $1,101,854 in June 2025. The MLS® Home Price Index Composite benchmark declined by approximately 5.4 per cent year over year.

The market is therefore not experiencing broad price growth yet. Instead, it appears to be moving from weaker conditions toward greater stability.

This distinction is important. Stronger sales do not automatically mean that every property will sell quickly or that sellers can increase their asking prices without supporting evidence. Buyers remain informed, selective, and sensitive to affordability. At the same time, they now face less inventory than they did one year ago.

The June market can be described as improving but still highly strategic. Buyers retain negotiating opportunities, while sellers benefit from stronger demand and reduced listing competition.

June 2026 Market Snapshot

The primary GTA market statistics for June 2026 were:

·         Total home sales: 6,770

·         Total sales dollar volume: $7,167,112,613

·         Average selling price: $1,058,658

·         Median selling price: $890,000

·         New listings: 17,282

·         Active listings: 27,329

·         Sales-to-new-listings ratio: 36.5 per cent

·         Months of inventory: 4.7

·         Average sale-to-list price ratio: 98 per cent

·         Average listing days on market: 29

·         Average property days on market: 42

Compared with June 2025:

·         Sales increased by 9.4 per cent

·         New listings decreased by 12.9 per cent

·         Active listings decreased by 13.5 per cent

·         The average selling price decreased by 3.9 per cent

·         Average listing days on market increased from 26 to 29 days

·         Average property days on market remained unchanged at 42 days

On a seasonally adjusted basis, sales increased from May to June, while new listings declined. The seasonally adjusted average selling price and MLS® HPI Composite also increased slightly from May.

These month-over-month movements do not establish a complete price recovery. They do, however, support the conclusion that the market continued to tighten through the spring.

First Half of 2026 Results

During the first six months of 2026, the GTA recorded:

·         31,149 home sales

·         $32,320,101,726 in total sales dollar volume

·         An average selling price of $1,037,597

·         A median selling price of $880,000

·         88,065 new listings

·         An average sale-to-list price ratio of 98 per cent

·         Average listing days on market of 31 days

·         Average property days on market of 47 days

Year-to-date sales were slightly higher than during the first half of 2025, while new listings were substantially lower. The year-to-date average price remained below the corresponding 2025 level.

The pattern across the first half of the year supports the view that 2026 has developed in two different stages.

The first quarter was slower, with limited transaction activity and considerable buyer caution. Conditions began to improve during the second quarter as more purchasers moved forward with buying decisions.

The market has not returned to the rapid pace experienced during previous high-growth periods. The improvement is more measured. Buyers are participating, but they continue to negotiate and compare properties carefully.

Demand Strengthened Across the GTA

The 9.4 per cent year-over-year increase in sales is the clearest evidence that buyer activity improved.

The City of Toronto recorded 2,443 sales in June 2026, compared with 2,303 in June 2025. The rest of the GTA recorded 4,327 sales, compared with 3,888 one year earlier.

The average selling price in the City of Toronto was $1,081,375. The average across the rest of the GTA was $1,045,832.

These figures illustrate that the recovery in activity was not limited to one section of the region. Both the 416 and 905 areas contributed to the increase in transactions.

The strength of demand varied by property type, price range, municipality, and neighbourhood. Some areas showed relatively fast sales and strong sale-to-list ratios. Others retained more inventory and longer selling periods.

A GTA-wide increase in sales should therefore not be interpreted as proof that every local market performed equally. Local property type, price, condition, and competition remain central to the outcome of an individual transaction.

Supply Declined as Buyer Activity Increased

The decline in both new and active listings is particularly important.

New listings fell by 12.9 per cent year over year. This means fewer properties were added to the market during June than during the same month in 2025.

Active listings fell by 13.5 per cent. This suggests that available inventory was being absorbed while the flow of new supply was also reduced.

For buyers, lower inventory means fewer alternatives to compare. Buyers still had considerable choice across the GTA, but that choice was smaller than one year earlier.

For sellers, lower inventory can improve visibility. A property may face fewer direct competitors, particularly when it is located in a desirable neighbourhood and falls within an active price range.

Reduced inventory does not guarantee a successful sale. The average property still required 29 listing days and 42 property days to sell. Buyers continued to reject homes that did not offer sufficient value.

What changed was the direction of the market. Supply and demand were moving closer together.

If sales continue to increase while inventory continues to decline, negotiating conditions could gradually become more favourable for sellers. If new listings increase substantially, buyers may regain a larger selection of alternatives.

Interpreting the Sales-to-New-Listings Ratio

The GTA sales-to-new-listings ratio was 36.5 per cent in June.

This ratio compares completed sales with the number of new properties entering the market. It provides one view of the relationship between demand and new supply.

A ratio of 36.5 per cent indicates that buyers were not absorbing new listings at a pace that would create widespread seller dominance. There remained enough new inventory for buyers to compare properties and negotiate.

The importance of the June result lies less in the ratio alone and more in the surrounding movement.

Sales increased. New listings decreased. Active listings decreased. Seasonally adjusted sales also rose month over month.

Taken together, these results show a market that was tightening, even though buyers still retained meaningful choice.

Months of Inventory and Market Pace

The GTA recorded 4.7 months of inventory in June.

Months of inventory estimates how long it would take to sell the current active inventory at the existing pace of sales if no new listings were added.

The 4.7-month figure reinforces the view that the market remained relatively balanced and selective. It was not characterized by severe scarcity across the entire region.

However, the GTA average can hide substantial differences.

Durham Region recorded 3.4 months of inventory, while the City of Toronto recorded 4.7 months. York Region and Peel Region each had approximately 5.1 months. Halton Region had 4.3 months.

Within individual municipalities, the differences were wider. Some locations had less than three months of inventory, while others had considerably more.

This variation means a seller’s strategy should not be based on the GTA figure alone. A detached home in Whitby, a condo apartment in Toronto Central, and a luxury property in King operate within different buyer pools and inventory conditions.

Price Direction Remains Cautious

The average GTA selling price was down 3.9 per cent year over year, while the MLS® HPI Composite benchmark declined by approximately 5.4 per cent.

The difference between these measures is important.

The average selling price is influenced by the mix of properties sold. If a larger proportion of expensive homes sells during one period, the average may rise even when underlying values are relatively unchanged. If more lower-priced properties sell, the average may fall.

The MLS® HPI is designed to track the value of a typical property with consistent characteristics. It can provide a more stable indication of price movement across time.

Both indicators were lower than one year earlier, confirming that GTA prices remained under annual pressure.

The rate of decline, however, had moderated compared with earlier periods. The seasonally adjusted average price increased slightly from May to June, and the seasonally adjusted HPI Composite also moved slightly higher.

This suggests that the market may be approaching a period of greater price stability. It does not confirm that sustained appreciation has begun.

Further evidence would be required across several months, including continued sales growth, reduced inventory, improving sale-to-list ratios, and a consistent upward movement in benchmark values.

MLS® Home Price Index Results

The June MLS® HPI data showed annual declines across the major property categories.

For all TRREB areas:

·         The Composite benchmark declined by approximately 5.4 per cent

·         The single-family detached benchmark declined by approximately 5.3 per cent

·         The single-family attached benchmark declined by approximately 5.1 per cent

·         The townhouse benchmark declined by approximately 7.4 per cent

·         The apartment benchmark declined by approximately 8.2 per cent

The larger declines in townhouses and apartments show that affordability-focused categories were not protected from price pressure.

In fact, condo apartment sales increased significantly while apartment benchmark prices remained well below last year. Buyers were willing to purchase more units, but they continued to demand lower prices.

This is a key feature of the June market: transaction activity improved before annual price growth returned.

Detached Home Market

Detached homes remained the largest segment of the GTA market.

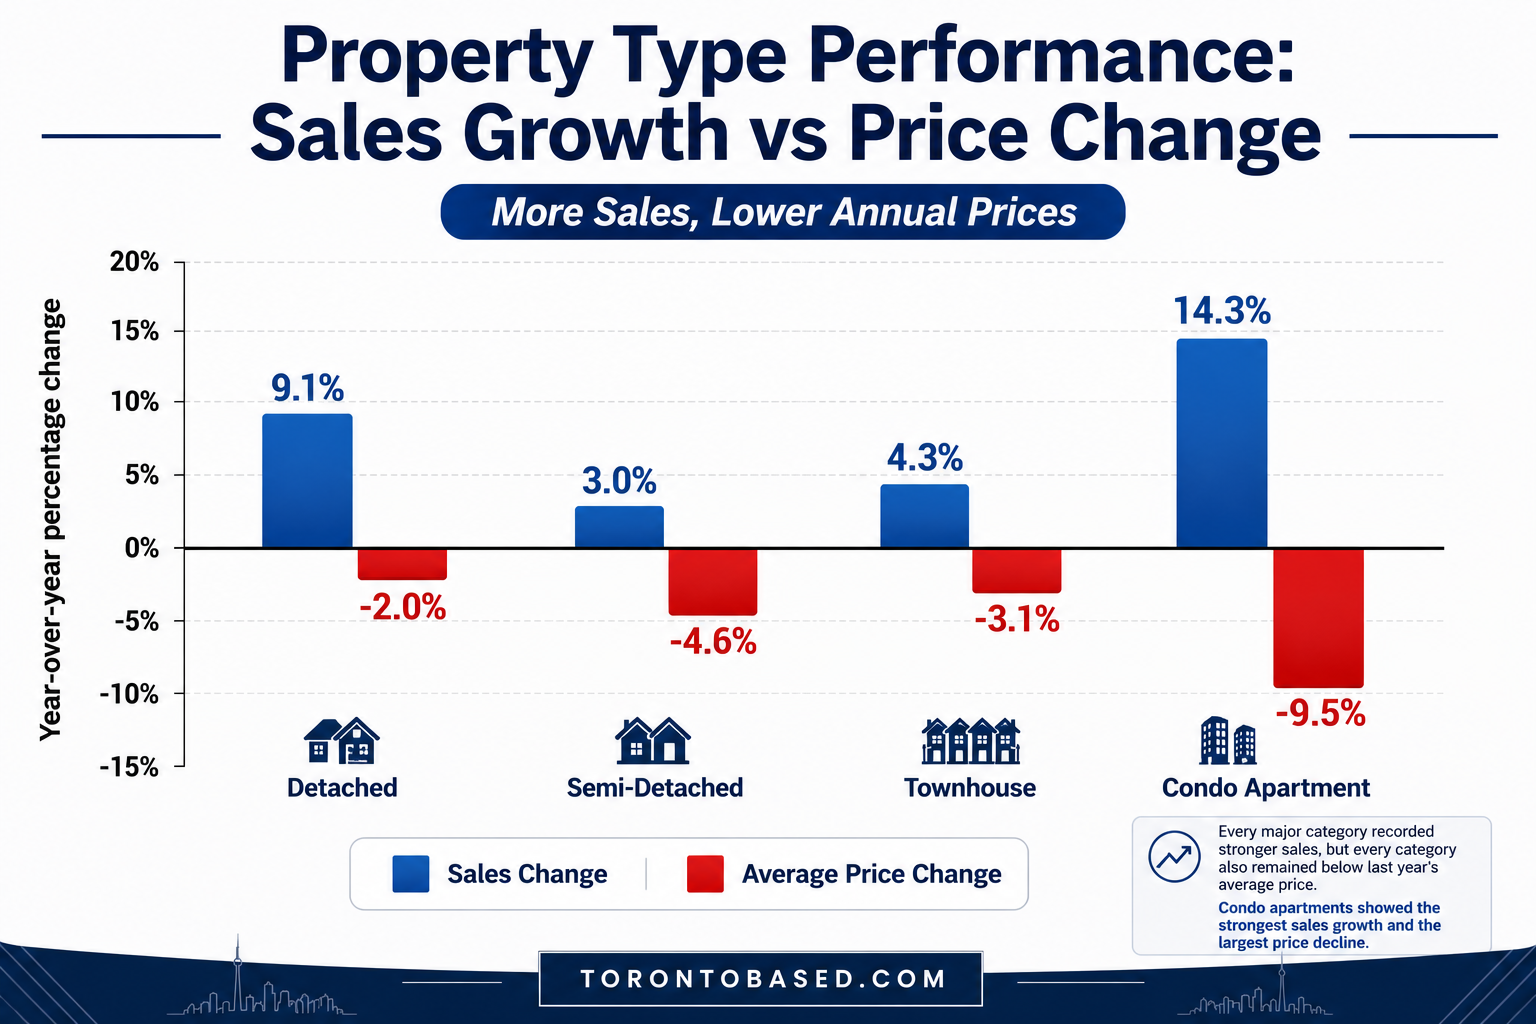
A total of 3,256 detached homes sold in June, accounting for 48.1 per cent of all transactions. Sales increased 9.1 per cent year over year.

The average detached price was $1,364,204, down 2.0 per cent from June 2025.

The geographic price difference was substantial:

·         City of Toronto detached average: $1,648,440

·         Rest of GTA detached average: $1,272,842

The detached market recorded:

·         8,470 new listings

·         12,635 active listings

·         An average sale-to-list ratio of 97 per cent

·         Average listing days on market of 25 days

·         A median price of $1,160,000

Detached homes experienced the smallest annual average-price decline among the four major property types. This suggests that demand for traditional family housing remained comparatively resilient.

Sellers should not interpret this as unrestricted pricing power. Buyers paid an average of 97 per cent of the list price, showing that negotiation remained common.

Detached properties with desirable layouts, updated interiors, suitable parking, finished basements, strong school access, and competitive pricing were better positioned to attract attention.

Properties with significant renovation requirements or ambitious asking prices faced greater resistance.

Semi-Detached Home Market

A total of 617 semi-detached homes sold in June, an increase of 3.0 per cent year over year.

The average semi-detached price was $1,038,973, down 4.6 per cent from June 2025.

The City of Toronto average was $1,264,782, compared with $863,272 across the rest of the GTA.

The semi-detached market recorded:

·         1,218 new listings

·         1,480 active listings

·         An average sale-to-list ratio of 102 per cent

·         Average listing days on market of 19 days

·         A median price of $910,888

The 102 per cent average sale-to-list ratio indicates that listing strategies within this segment often resulted in properties selling above their asking prices.

This does not mean every semi-detached home sold in competition. It may reflect the use of lower asking prices intended to attract multiple offers in certain neighbourhoods.

Semi-detached sellers should therefore evaluate both sale price and list strategy when reviewing comparable properties. A sale above asking does not automatically mean the property sold above market value.

Townhouse Market

The broader townhouse category reported 1,082 sales, an increase of 4.3 per cent year over year.

The average townhouse price was $844,579, down 3.1 per cent.

The City of Toronto townhouse average was $973,232, compared with $808,495 in the rest of the GTA.

Within the attached or row townhouse category, 619 properties sold at an average price of $912,380. Condo townhouses recorded 463 sales at an average price of $753,933.

The difference between freehold-style attached townhouses and condo townhouses is important for buyers.

A freehold townhouse may involve fewer monthly fees but can require the owner to manage exterior maintenance directly. A condo townhouse may have a lower purchase price but includes monthly condominium fees and shared governance.

Buyers should compare the full cost of ownership rather than focusing only on the purchase price.

For sellers, the competing alternatives matter. A townhouse may compete with small detached homes, semi-detached properties, larger condo apartments, and other townhouse formats.

Pricing and presentation must account for what the same buyer can purchase elsewhere.

Condo Apartment Market

Condo apartments recorded the strongest increase in transaction activity.

A total of 1,714 condo apartments sold, up 14.3 per cent year over year. The average price was $630,688, down 9.5 per cent.

The City of Toronto average was $665,760, while the rest of the GTA averaged $563,874.

The condo apartment market recorded:

·         4,550 new listings

·         8,630 active listings

·         An average sale-to-list ratio of 97 per cent

·         Average listing days on market of 38 days

·         A median price of $540,000

Condo apartments represented 25.3 per cent of total June sales.

The 14.3 per cent increase in transactions indicates that more purchasers were willing to enter the condo market. The 9.5 per cent decline in average price shows that affordability remained central to that activity.

Condo buyers were likely to compare multiple units and buildings before making decisions. Important factors include:

·         Maintenance fees

·         Unit size

·         Parking and locker availability

·         Building condition

·         Reserve fund strength

·         Floor plan

·         Exposure and floor level

·         Transit access

·         Amenities

·         Management quality

·         Upcoming repairs or assessments

Condo sellers face a market where similar units can be compared closely. Professional photography, accurate measurements, clear fee information, proper preparation, and realistic pricing are especially important.

Regional Market Differences

The GTA is not one uniform housing market.

June statistics varied considerably across the major regions.

City of Toronto

The City of Toronto recorded:

·         2,443 sales

·         An average price of $1,081,375

·         A median price of $835,000

·         6,096 new listings

·         10,047 active listings

·         4.7 months of inventory

·         A 99 per cent sale-to-list ratio

·         29 LDOM

·         38 PDOM

York Region

York Region recorded:

·         1,289 sales

·         An average price of $1,169,958

·         A median price of $1,050,888

·         3,293 new listings

·         5,302 active listings

·         5.1 months of inventory

·         A 98 per cent sale-to-list ratio

·         29 LDOM

·         45 PDOM

Peel Region

Peel Region recorded:

·         1,167 sales

·         An average price of $966,024

·         A median price of $875,000

·         3,267 new listings

·         5,189 active listings

·         5.1 months of inventory

·         A 98 per cent sale-to-list ratio

·         29 LDOM

·         48 PDOM

Durham Region

Durham Region recorded:

·         849 sales

·         An average price of $856,170

·         A median price of $805,000

·         2,049 new listings

·         2,637 active listings

·         3.4 months of inventory

·         A 99 per cent sale-to-list ratio

·         24 LDOM

·         36 PDOM

Halton Region

Halton Region recorded:

·         785 sales

·         An average price of $1,222,898

·         A median price of $1,060,000

·         1,846 new listings

·         2,827 active listings

·         4.3 months of inventory

·         A 97 per cent sale-to-list ratio

·         28 LDOM

·         41 PDOM

These results illustrate why local analysis is required before making a pricing or purchasing decision.

Durham had a lower average price and less inventory than several other regions. Halton had a higher average price and a lower sale-to-list ratio. York had higher prices and more inventory. Toronto contained large differences between West, Central, and East districts.

No regional average should be treated as a substitute for neighbourhood-level comparable sales.

Buyer Behaviour in June 2026

Buyers became more active, but they did not become careless.

The increase in sales confirms that more purchasers were prepared to complete transactions. The decline in average prices, the 98 per cent sale-to-list ratio, and the 29-day average listing period confirm that buyers continued to negotiate.

The modern buyer has access to extensive information. Buyers can compare:

·         Active listings

·         Recent sales

·         Price reductions

·         Listing history

·         Property days on market

·         Neighbourhood alternatives

·         Property taxes

·         Maintenance fees

·         Renovation requirements

·         Financing costs

This access to information affects how quickly buyers respond.

A home that is well priced and well presented may attract attention shortly after launch. A property that appears overpriced may receive few showings even when the broader market is improving.

Buyers are not simply asking whether they like a home. They are asking whether it represents better value than other available options.

Buyer Strategy

Buyers should approach the second half of 2026 with preparation rather than urgency.

Establish a Reliable Budget

The June dataset reported:

·         Bank of Canada overnight rate: 2.3 per cent

·         Prime rate: 4.5 per cent

·         One-year mortgage rate: 5.49 per cent

·         Three-year mortgage rate: 6.05 per cent

·         Five-year mortgage rate: 6.09 per cent

Financing remained a major affordability consideration.

Buyers should understand the difference between the amount a lender may approve and the monthly payment they can manage comfortably.

Property taxes, utilities, insurance, condominium fees, repairs, transportation costs, and future maintenance should be included in the budget.

Review Comparable Sales

Asking prices do not establish market value.

Buyers should examine recent sales of properties with similar size, condition, location, lot, parking, and features.

Active listings are useful for understanding competition, but sold listings provide better evidence of what buyers have recently paid.

Understand Listing History

The difference between LDOM and PDOM can reveal important information.

A listing may appear new because it has been cancelled and relisted. The property may have been exposed to buyers for a longer period than the current listing indicates.

Reviewing the complete history can help buyers understand seller expectations and possible negotiating flexibility.

Move Decisively on Strong Properties

A market with fewer listings can create competition for the best homes.

Buyers should not assume that every seller will accept a substantial discount. A property that is priced accurately may attract multiple interested purchasers even when the GTA average remains below last year.

Preparation allows a buyer to act without making an emotional decision.

Seller Behaviour in June 2026

Sellers entered a more constructive market, but they still needed to earn buyer attention.

Higher sales and lower inventory created a stronger environment than one year earlier. Prices, however, remained below June 2025 levels.

A seller who focuses only on improving transaction activity may set an asking price above what current comparable sales support.

That can result in:

·         Reduced showing activity

·         Extended days on market

·         Price reductions

·         Cancellation and relisting

·         Weaker negotiating leverage

·         Buyer concern about the property

Improving market conditions should support a stronger strategy, not unrealistic expectations.

Seller Strategy

Use Current Evidence

Pricing should be based on recent local sales, current competition, market time, condition, and buyer response.

The original purchase price, renovation expense, mortgage balance, or desired proceeds do not determine current market value.

Prepare Before Listing

The first days of a listing often generate the greatest attention.

Before launch, sellers should address cleaning, decluttering, repairs, staging, photography, descriptions, measurements, documents, showing arrangements, and marketing materials.

A listing should not be used to test the market before the property is ready.

Position the Property Clearly

Buyers should be able to understand quickly:

·         What makes the property valuable

·         How it compares with competing listings

·         Which features are included

·         Whether improvements were completed

·         What costs are associated with ownership

·         Why the asking price is reasonable

Clear positioning reduces uncertainty and strengthens buyer confidence.

Respond to Market Feedback

A listing strategy should be reviewed after launch.

Showing activity, online engagement, buyer comments, competing listings, new sales, and offers provide useful information.

If the market response is consistently weak, the seller should determine whether the problem relates to price, condition, access, presentation, or marketing.

Waiting without adjusting can reduce momentum.

Investor Considerations

June presented a combination of improving liquidity and lower annual prices.

More properties sold, which can make future resale easier if transaction activity continues to improve. Prices remained below last year, which may create acquisition opportunities.

The dataset does not include rental income, vacancy, operating costs, or property-specific financing. Those figures must be assessed separately.

Investors should evaluate:

·         Purchase price

·         Down payment

·         Financing cost

·         Property tax

·         Insurance

·         Maintenance

·         Condominium fees

·         Repairs

·         Vacancy allowance

·         Management expenses

·         Legal use

·         Expected rental income

·         Holding period

·         Exit strategy

A property should not depend entirely on future appreciation to justify the investment.

Improving market momentum is useful, but a strong investment must remain financially sustainable if prices stay relatively stable.

Market Risks

Several risks could alter the current direction.

New Listings Could Increase

Stronger sales may encourage more homeowners to list.

If new supply increases faster than buyer demand, inventory could rise and sellers could face greater competition.

Employment Conditions Could Affect Confidence

The dataset reported Toronto unemployment of 7.6 per cent and employment growth of 0.7 per cent.

Employment uncertainty can delay purchases, reduce borrowing capacity, and affect consumer confidence.

Inflation and Financing Remain Important

Inflation was reported at 3.2 per cent.

Even with a lower overnight rate, mortgage payments remain substantial. Financing qualification and monthly affordability may continue to limit buyer demand.

Price Expectations Could Move Ahead of the Market

If sellers raise prices before the data supports stronger values, sales momentum could slow.

A market can experience more transactions without immediate price appreciation. Pricing discipline remains essential.

What to Watch Next

The second half of 2026 should be evaluated through several connected indicators.

Sales

Continued year-over-year sales growth would support the view that buyer confidence is strengthening.

New Listings

A continued decline in new listings would place additional pressure on available supply. A substantial increase would give buyers more alternatives.

Active Inventory

Falling active inventory would indicate that demand continues to absorb supply.

Days on Market

A decline in LDOM and PDOM would suggest that properties are selling more efficiently. A growing gap between the two may indicate more cancellations and relistings.

Sale-to-List Ratio

A rising ratio would show that buyers are moving closer to seller expectations.

Average Price and HPI

These indicators should be reviewed together. Several months of consistent improvement would provide stronger evidence of price stabilization.

Property Type Performance

Condo apartments, townhouses, semi-detached homes, and detached properties may recover at different rates. Affordability will continue to influence where buyers concentrate their activity.

Practical Meaning for Buyers

June still provided buyers with opportunities.

Prices remained below last year. The market offered thousands of active listings. The average sale-to-list ratio remained below 100 per cent across the market as a whole.

Buyers should not interpret improving sales as a reason to rush. They should interpret declining inventory as a reason to become organized.

A financially prepared buyer can still negotiate while responding quickly when a suitable property is priced correctly.

Practical Meaning for Sellers

Sellers benefited from stronger demand and less active competition.

The opportunity was greatest for homes that entered the market with realistic pricing, professional preparation, and a clear marketing plan.

The June results do not support the assumption that all lost value has been recovered. The average price and HPI benchmark remained below last year.

Sellers should position their properties for the current market rather than pricing for a future recovery that has not yet occurred.

Practical Meaning for Investors

Investors may find opportunities where weaker annual prices overlap with improving sales activity.

The strongest acquisitions will be those supported by realistic cash flow, manageable financing, and a clear long-term strategy.

A tightening market may improve future resale conditions, but it should not replace property-level due diligence.

A Market Moving Toward Greater Stability

June 2026 showed that the GTA housing market was gaining momentum.

Sales increased by 9.4 per cent. New listings declined by 12.9 per cent. Active inventory fell by 13.5 per cent. Seasonally adjusted sales rose from May, while new listings declined.

Prices remained below last year, but the annual decline moderated and seasonally adjusted measures moved slightly higher month over month.

These conditions point to a market transitioning from weakness toward greater stability.

Buyers still have negotiating opportunities, but the supply of available homes is becoming smaller.

Sellers have a stronger opportunity to attract buyers, but pricing and presentation remain decisive.

Investors have access to lower annual prices and improving liquidity, but every acquisition must be supported by sound financial analysis.

Request a Personalized Market Analysis

GTA statistics provide important direction, but they cannot determine the correct value or strategy for one specific property.

Your neighbourhood, property type, size, condition, lot, renovations, parking, layout, comparable sales, and active competition all affect the result.

A personalized market analysis can provide:

·         Recent comparable sales

·         Current competing listings

·         Local price trends

·         Days-on-market patterns

·         Property type performance

·         Buyer demand

·         Pricing position

·         Preparation recommendations

·         Marketing strategy

·         Negotiation considerations

For a detailed review of your property, buying plans, or investment opportunity, request a personalized analysis based on the June 2026 market data and the most relevant local comparables.

The market is improving, but successful decisions still depend on understanding how the broader trend applies to your specific situation.


🏡 Ready to Start Your Real Estate Journey?
Whether you're planning to buy, sell, or invest, I’m here to guide you every step of the way — surprises and all.

📈 Looking to capitalize on today’s changing market?
Explore a wide range of specialized listings with access to powerful tools and search portals tailored to your needs:

·         🛢️ Gas Stations for Sale

·         🏢 Commercial & Industrial Properties

·         🏠 Residential Homes Across the GTA

·         🏨 Hotels & Motels Investment Opportunities

·         🏗️ Pre-Construction Condo Projects

·         🏙️ Condo Resale Listings in the GTA

Stay ahead of the curve. Get the latest real estate news and insights right here.


📩 Need help navigating your options?
Reach out for expert advice and market insights:

Sami Chowdhury
BROKER
📧 Email: samichy@torontobase.com
🌐 Web: www.torontobased.com | www.torontobase.ca

Let’s make your next move a smart one.


Get more market insights here:

·         Renting vs. Owning: How $2,500/Month Could Cost You $190,000

·         The GTA Housing Market Is Changing: What May 2026 Means for Buyers, Sellers, and Investors

·         GTA Real Estate Market Update – April 2026

·         Durham Region Real Estate Market Report – October 2025

·         GTA Housing Market Update – August 2025

·         Mississauga Condo & Condo Townhouse Market Report – Q3 2025

·         Bill 60 vs. Ontario’s Residential Tenancies Act (RTA): What’s Changing?

Stay ahead of the curve. Get the latest real estate news and insights right here.


Read

34 Marilake Drive – A Rare Opportunity to Own a Beautifully Renovated Family Home in the Heart of Agincourt

34 Marilake Drive, Toronto, ON

If you've been searching for a home that combines space, comfort, convenience and long-term value, 34 Marilake Drive deserves your attention. Nestled on a premium 55-foot frontage lot in one of Scarborough's most established and desirable communities, this beautifully renovated detached home offers the perfect balance of modern living and future potential.

Whether you're a growing family, a multi-generational household, or simply looking for a move-in-ready home in a mature neighbourhood, this property delivers exceptional value in today's Toronto real estate market.

Click here to view the listing on MLS


A Home Designed for Family Living

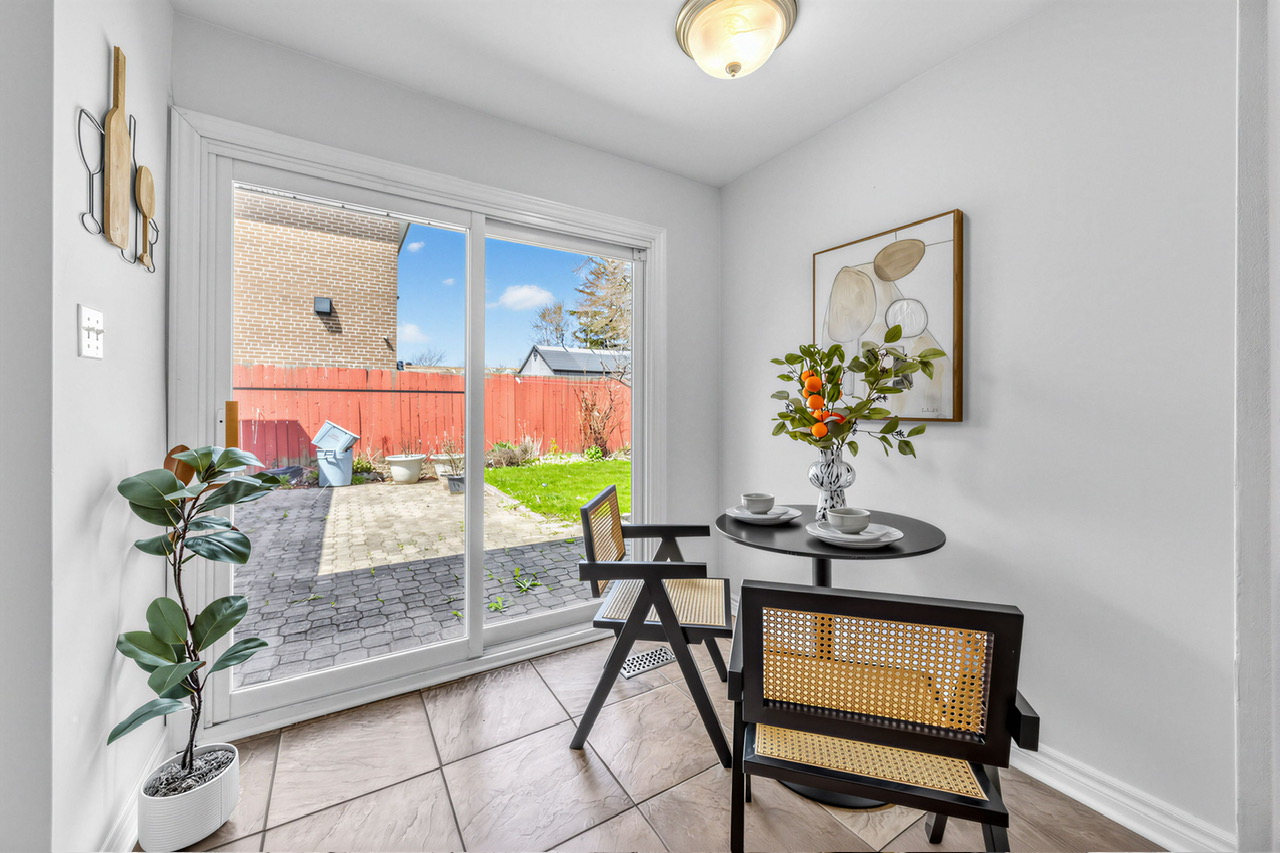
From the moment you arrive, you'll appreciate the curb appeal of this classic all-brick detached backsplit. Set on a generous lot measuring approximately 55 x 104 feet, the property provides ample outdoor space while maintaining privacy and functionality.

Inside, the home offers:

  • 3 spacious bedrooms on the upper level

  • 2 additional bedrooms in the finished lower level

  • 2 updated bathrooms

  • Bright living and dining areas

  • Renovated kitchen

  • Finished basement

  • Double attached garage

  • Parking for up to five vehicles

The flexible floor plan makes this home ideal for today's lifestyle. Whether you need extra bedrooms, a home office, guest accommodations or recreational space, the lower level offers endless possibilities.


Beautifully Renovated and Move-In Ready

Finding a home that's already been tastefully updated can save buyers significant time, money and stress.

34 Marilake Drive has been thoughtfully renovated, allowing the next owner to move in and immediately begin enjoying the home.

The bright interior creates a warm and welcoming atmosphere, while the functional layout makes everyday living effortless.

Recent improvements include:

  • Roof replaced in 2019

  • Windows updated in 2016

  • Updated bathrooms

  • Renovated kitchen

  • Finished lower level

  • California shutters

  • Central air conditioning

The result is a home that offers modern comfort while retaining the solid craftsmanship of a classic brick construction.

Click here to view the listing on MLS


Space That Grows With Your Family

One of the biggest advantages of this property is flexibility.

Many buyers today are searching for homes that can adapt to changing lifestyles.

The additional lower-level bedrooms can easily become:

  • Guest rooms

  • Children's bedrooms

  • Home offices

  • Hobby rooms

  • Fitness areas

  • Study rooms

  • Multi-generational living space

This versatility makes the home attractive to families at every stage of life.


Premium 55-Foot Lot

Large lots are becoming increasingly difficult to find in Toronto.

The approximately 55-foot frontage provides numerous benefits.

The expansive backyard creates the perfect setting for:

  • Summer BBQs

  • Family gatherings

  • Gardening

  • Outdoor entertaining

  • Children's play area

  • Pet-friendly space

The generous side yard further enhances the property's appeal and provides additional outdoor flexibility.

Click here to view the listing on MLS


A Highly Desirable Agincourt Location

Location continues to be one of the most important factors when purchasing real estate.

34 Marilake Drive is situated in the heart of Agincourt, one of Scarborough's most established and family-friendly neighbourhoods.

Residents enjoy convenient access to:

  • Highway 401

  • Highway 404

  • Don Valley Parkway

  • TTC bus routes

  • Scarborough Town Centre

  • Agincourt Mall

  • Grocery stores

  • Restaurants

  • Community centres

  • Libraries

  • Medical facilities

  • Parks and recreational amenities

Daily commuting throughout the GTA is both convenient and efficient.


Excellent Schools Nearby

For families, school quality is often a deciding factor.

The property is located within the catchment area of respected local schools, including:

  • C.D. Farquharson Junior Public School

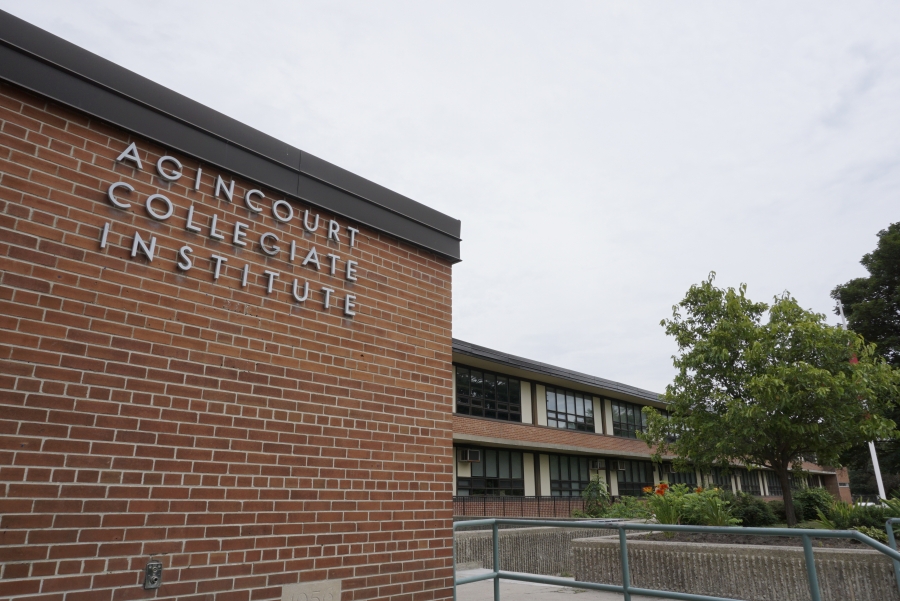
  • Agincourt Collegiate Institute

These schools continue to make the neighbourhood attractive for families seeking long-term stability.


Exciting Future Transit Improvements

One of the most exciting aspects of this location is its future transportation connectivity.

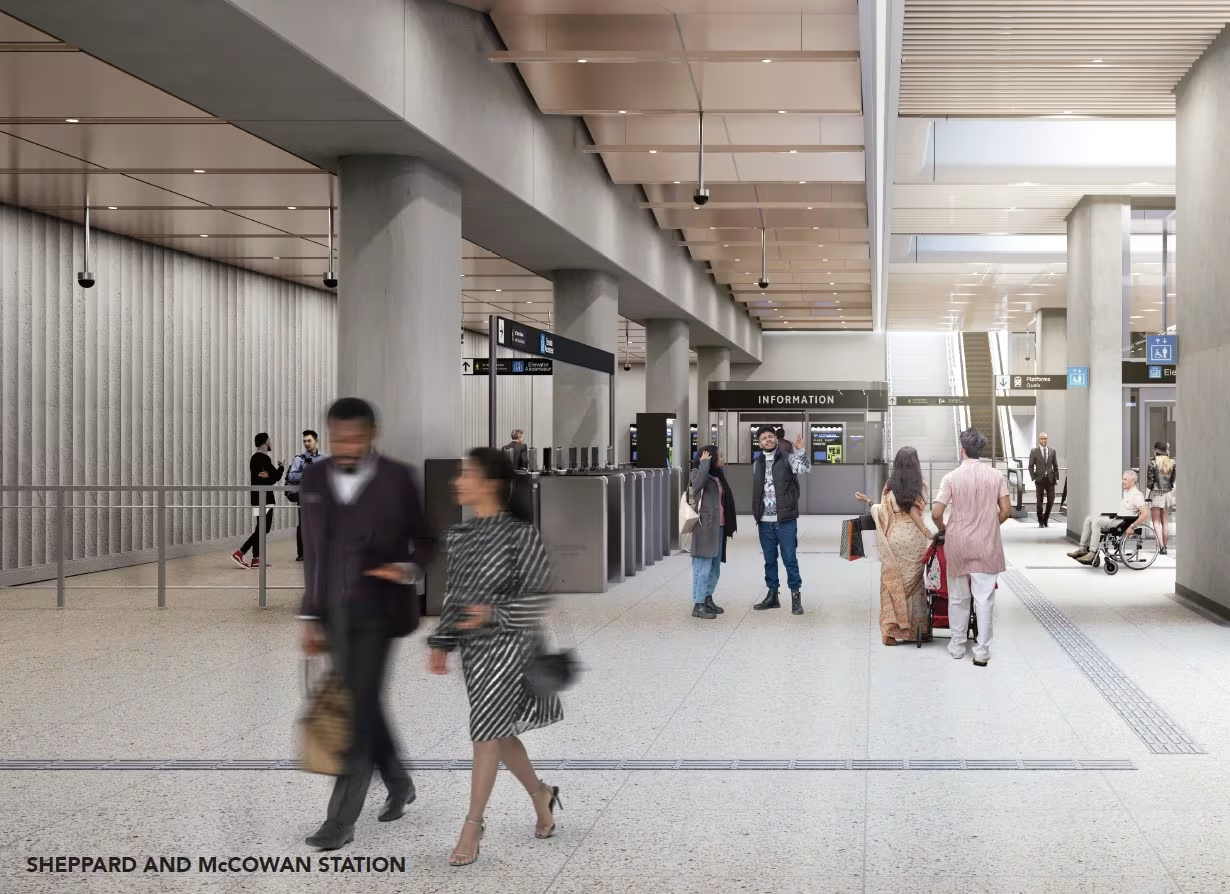
The property is located just minutes from the planned Sheppard–McCowan Station, which will form part of the Scarborough Subway Extension. This major infrastructure project is expected to improve rapid transit access for residents and strengthen connectivity across the city.

In addition, the proposed Sheppard East LRT, currently in the planning stage, has the potential to further enhance east-west transit along the Sheppard corridor. While planning and implementation remain subject to government approvals and funding, these future transit investments highlight the long-term appeal of the area.

Improved transit infrastructure can enhance convenience for residents and contribute to the continued desirability of well-located neighbourhoods over time.

Click here to view the listing on MLS


A Mature Community with Lasting Appeal

Unlike many newer subdivisions, Agincourt offers:

  • Mature tree-lined streets

  • Established parks

  • Long-standing community amenities

  • Diverse dining options

  • Excellent shopping

  • Strong neighbourhood character

It is a community where families have chosen to live for generations.

Click here to view the listing on MLS


Room to Create Your Own Lifestyle

Every family lives differently.

The beauty of this home lies in its adaptability.

Host holiday dinners.

Create a home theatre.

Set up a dedicated home office.

Design the backyard you've always wanted.

Enjoy quiet evenings in a peaceful neighbourhood while remaining connected to every major convenience Toronto has to offer.


Why Buyers Will Love This Home

✔ Beautifully renovated

✔ Premium 55-foot lot

✔ Detached all-brick home

✔ 3+2 bedrooms

✔ 2 updated bathrooms

✔ Finished basement

✔ Double attached garage

✔ Parking for five vehicles

✔ Roof replaced in 2019

✔ Windows updated in 2016

✔ Excellent school district

✔ Minutes to Highway 401

✔ Convenient TTC access

✔ Close to Scarborough Town Centre

✔ Near the future Sheppard–McCowan Station on the Scarborough Subway Extension

✔ Future Sheppard East LRT corridor planned nearby

Click here to view the listing on MLS


Schedule Your Private Viewing

Homes that combine thoughtful renovations, generous living space, premium lot size and outstanding location are increasingly difficult to find in Toronto.

34 Marilake Drive presents a unique opportunity to own a beautifully maintained family home in one of Scarborough's most desirable neighbourhoods, while benefiting from both today's conveniences and tomorrow's planned transit improvements.

Whether you're searching for your forever home or simply the right place for your next chapter, 34 Marilake Drive is a property that deserves to be experienced in person.

To schedule your private viewing or to learn more about this exceptional property, contact Sami Chowdhury today.

Click here to view the listing Details


🏡 Ready to Start Your Real Estate Journey?
Whether you're planning to buy, sell, or invest, I’m here to guide you every step of the way — surprises and all.

📈 Looking to capitalize on today’s changing market?
Explore a wide range of specialized listings with access to powerful tools and search portals tailored to your needs:

Stay ahead of the curve. Get the latest real estate news and insights right here.


📩 Need help navigating your options?
Reach out for expert advice and market insights:

Sami Chowdhury
BROKER
📧 Email: samichy@torontobase.com
🌐 Web: www.torontobased.com | www.torontobase.ca

Let’s make your next move a smart one.


Get more market insights here:

Stay ahead of the curve. Get the latest real estate news and insights right here.


Read

The GTA Housing Market Is Changing: What May 2026 Means for Buyers, Sellers, and Investors

GTA Housing Market May 2026: The Recovery Signals Are Getting Stronger

For much of the past two years, conversations about the Greater Toronto Area housing market have centered on uncertainty. Buyers questioned affordability. Sellers questioned timing. Investors questioned future returns. Rising borrowing costs, economic uncertainty, and changing consumer confidence created an environment where many participants chose caution over action.

May 2026 introduced a different conversation.

The latest GTA market data suggests that the market may be entering a new phase. Not a dramatic surge. Not a return to the extreme conditions experienced during previous boom cycles. Instead, the data points toward something potentially more sustainable: a gradual strengthening of demand occurring at the same time as inventory is becoming more constrained.

This combination deserves attention because it often represents the earliest stage of a market transition.

The headline numbers immediately stand out. GTA home sales increased to 6,583 transactions during May 2026, representing a 6.3 percent increase compared to May 2025. At the same time, new listings entering the market declined by 18.9 percent. The average selling price reached $1,069,700, while seasonally adjusted sales increased 10 percent compared to April.

Individually, each of these numbers provides useful information. Together, they tell a much more important story.

The relationship between demand and supply is changing.

For buyers, sellers, investors, and homeowners alike, understanding this shift may become increasingly important during the second half of 2026.

Why Sales Growth Matters More Than the Headline Price

Whenever market reports are released, average price tends to receive the most attention.

In May 2026, the average GTA selling price remained 4.6 percent below the same period last year. At first glance, some observers may interpret this as a sign of continued weakness.

A closer look suggests the situation is more nuanced.

Prices are typically a lagging indicator. Sales activity often changes direction before prices fully respond. Buyer confidence tends to return gradually. Inventory begins to tighten. Competition increases. Only after these developments become sustained do prices begin to reflect the changing balance between supply and demand.

This is why the increase in sales activity may be one of the most important signals contained within the May report.

The market recorded 6,583 transactions during the month. More importantly, sales increased not only compared to last year but also compared to April on a seasonally adjusted basis. The 10 percent month over month increase suggests momentum is improving rather than simply benefiting from seasonal spring activity.

When more buyers enter the market while fewer properties become available, the foundation for future price stabilization begins to develop.

That does not guarantee immediate appreciation. Markets rarely move in straight lines. However, it often marks the point where downward pressure begins to weaken.

For homeowners who have been waiting for signs of market improvement, this shift deserves attention.

Inventory Is Becoming the Story

Many market participants focus almost entirely on buyer demand.

Yet demand is only half the equation.

Supply often determines whether increased buyer activity translates into stronger pricing or merely increased browsing activity.

May's data reveals a significant inventory story.

New listings declined by 18.9 percent compared to the same month last year. This is not a minor adjustment. It represents a meaningful reduction in the number of homes entering the marketplace.

This decline occurred while sales were increasing.

When economists, analysts, and experienced real estate professionals discuss market tightening, this is exactly the type of relationship they monitor.

Demand moving higher.

Supply moving lower.

Inventory being absorbed.

The practical effect becomes visible at the street level.

Buyers begin noticing fewer comparable properties available within their preferred neighbourhoods.

Sellers begin experiencing stronger showing activity.

Properties that are properly priced receive faster attention.

Competition gradually increases for the most attractive listings.

The market does not suddenly become a seller's market overnight. Instead, the balance slowly shifts.

May 2026 may represent one of those important transitional moments.

The Market Is Not Uniform

One of the biggest mistakes people make when evaluating housing data is assuming the GTA behaves as a single market.

In reality, the Greater Toronto Area functions as dozens of interconnected markets.

York Region operates differently from Toronto East.

Toronto West behaves differently from Niagara.

Waterloo differs from Durham.

Condominiums respond differently than detached homes.

This is why broad GTA statistics provide direction rather than certainty.

The regional reports contained within the May dataset highlight significant differences across municipalities.

York Region continued to demonstrate strong pricing levels, with average prices exceeding $1.17 million. York also maintained substantial listing activity and transaction volume, reinforcing its importance as one of the GTA's largest and most influential housing markets.

Toronto East and Toronto West continued attracting strong buyer demand, benefiting from their proximity to employment centres, transit infrastructure, and established neighbourhoods.

Waterloo and Wellington continued reflecting different affordability dynamics compared to core GTA markets.

Meanwhile, regions such as Niagara and Northumberland continue attracting attention from buyers seeking relative affordability and lifestyle considerations.

These regional variations matter because buyer decisions increasingly depend on value comparisons.

A buyer considering a detached home in York Region may evaluate alternatives in Durham.

A condominium purchaser may compare downtown Toronto options with suburban alternatives.

An investor may compare rental opportunities across multiple municipalities before committing capital.

The result is a highly interconnected market where local conditions influence broader GTA performance.

What Buyers Are Really Looking For

The May data also reflects a behavioural shift that has become increasingly important.

Today's buyers are informed.

They have access to property data, comparable sales, online listings, neighbourhood research, mortgage calculators, market reports, and professional advice.

This access to information has fundamentally changed how buyers behave.

During periods of extreme market competition, buyers often focus on securing any property that meets basic requirements.

Balanced markets create different behaviour.

Buyers become selective.

They compare.

They negotiate.

They wait.

They evaluate alternatives carefully.

The increase in average days on market and property days on market observed across many areas supports this reality.

Buyers are not disappearing.

They are becoming more deliberate.

Properties that offer clear value continue attracting activity.

Properties that appear overpriced often struggle.

Homes requiring substantial work face greater scrutiny.

Presentation becomes more important.

Pricing becomes more important.

Marketing becomes more important.

This behavioural shift is likely to remain one of the defining characteristics of the 2026 market.

Rather than emotional buying, the market increasingly rewards informed decision making.

FAQs

1. How many homes sold in the GTA during May 2026?
6,583 homes sold across the GTA.

2. Did home sales increase in May 2026?
Yes. Sales increased 6.3% year over year.

3. What was the average GTA home price?
$1,069,700.

4. Are prices higher or lower than last year?
Average prices were 4.6% lower than May 2025.

5. What happened to new listings?
New listings declined 18.9%.

6. Is inventory tightening?
Yes. Sales increased while listings declined.

7. Is it a seller's market?
The market is becoming more balanced but is not yet a full seller's market.

8. What is the biggest trend to watch?
The combination of rising demand and declining inventory.


📊 Latest Market Insights (Updated Monthly)

✔️ Toronto & GTA Housing Market — May 2026

✔️ Rent vs Own in Toronto (2026): What Happens After 25 Years? A Real Numbers Breakdown!

✔️ Renting vs. Owning: How $2,500/month could cost you $190,000
✔️ GTA Housing — GTA Buyer Guide 2026
✔️ Mississauga Condo Market — Q3 2025
✔️ Durham Region Market Report — Oct 2025
✔️ Bill 60 vs Ontario RTA — What’s Changing?

👉 Read more market reports & analysis →


🏡 Thinking of Buying, Selling, or Investing in the GTA?
Don’t guess—use real data, real listings, and expert guidance.

🔍 Start Exploring Now (Live Search Portals)

👉 Gas Stations for Sale
👉
Commercial & Industrial Properties
👉
Residential Homes Across the GTA
👉
Hotels & Motels – Investment Opportunities
👉
Pre-Construction Condo Projects
👉
Condo Resale Listings (GTA)

📈 Market is shifting—smart investors move early.


📩 Need Clarity Before You Move?

Get straight answers, not sales pressure.

Sami Chowdhury | Broker

Ph: 647-725-0606
📧 samichy@torontobase.com
🌐 torontobased.com | torontobase.ca

Let’s turn market uncertainty into opportunity.

RE/MAX REALTRON REALTY INC, BROKERAGE

209-885 PROGRESS AVE, TORONTO, ON M1H3G3

Ph: 416-289-3333 / Fax: 416-289-4535


Contact Me, If you are planning to buy, sell, or invest in the GTA, the most important step is understanding where your property or budget fits within these changing conditions.

I can prepare a detailed, data driven breakdown tailored to your situation so you can move forward with clarity and confidence.


Read

GTA Real Estate Market Update – April 2026

The Greater Toronto Area housing market showed renewed momentum in April 2026 as buyer activity increased while the number of new listings declined. This shift is important because it suggests that the market may be slowly moving away from the softer conditions experienced over the past year and toward a more balanced environment in certain neighbourhoods and housing segments.

According to the Toronto Regional Real Estate Board (TRREB), GTA REALTORS® reported 5,946 home sales in April 2026, representing a 7 percent increase compared to April 2025. At the same time, new listings declined by 9.3 percent year over year to 17,097.

This combination of rising sales and declining inventory is one of the first stronger indicators that demand may be stabilizing after a prolonged period of uncertainty driven by affordability challenges, elevated borrowing costs, economic concerns, and geopolitical uncertainty.

Average Home Prices Continue to Decline

Despite stronger sales activity, home prices remained lower compared to last year. The average GTA selling price in April 2026 was $1,051,969, down 4.9 percent from April 2025 when the average price stood at $1,106,505.

The MLS® Home Price Index Composite benchmark declined even further, falling 6.6 percent year over year.

For buyers, this has created improved affordability opportunities compared to the highly competitive market conditions seen during earlier market cycles. Lower prices combined with lower borrowing costs compared to last year have encouraged some buyers to return to the market this spring.

However, sellers are still facing a market where pricing strategy matters significantly. Buyers are carefully comparing properties, negotiating aggressively, and avoiding listings perceived as overpriced.

Detached Homes Continue to Lead the Market

Detached properties continued to command the highest average selling prices across the GTA.

TRREB reported the following average prices by property type in April 2026:

  • Detached: $1,372,688

  • Semi Detached: $1,033,469

  • Townhouse: $839,509

  • Condo Apartment: $635,653

Detached homes also accounted for the largest share of sales activity with 2,759 transactions reported across the GTA. Condo apartments followed with 1,553 sales, while townhouses recorded 985 sales and semi detached homes recorded 563 sales.

What stands out is the continued relative affordability gap between condos and detached homes. Many first time buyers who remain priced out of detached properties continue to focus on condo apartments and townhouses as entry points into the market.

Toronto vs Rest of GTA

The City of Toronto and surrounding GTA regions continued to show different pricing dynamics.

In the City of Toronto:

  • Average selling price: $1,091,761

  • Sales: 2,312

  • New listings: 6,136

In the Rest of GTA regions:

  • Average selling price: $1,026,653

  • Sales: 3,634

  • New listings: 10,961

This pricing gap continues to encourage some buyers to move toward suburban markets where they can obtain larger homes for lower prices. Areas in Durham, Peel, York, and Halton continue attracting buyers searching for more space and improved affordability.

Condo Market Remains Under Pressure

The condo market remains one of the more challenging segments in the GTA.

Condo apartment prices averaged $635,653 in April 2026, down 6.3 percent year over year.

Several factors continue impacting the condo segment:

  • Investor caution

  • Higher carrying costs

  • Slower rent growth compared to previous years

  • Increased competition among condo sellers

  • Greater inventory availability in many condo-heavy areas

At the same time, lower condo prices are creating opportunities for first time buyers and long term investors who were previously unable to enter the market.

Market Psychology Is Changing

One of the most important developments is not just the numbers themselves, but the psychology behind them.

For much of the past year, many buyers remained hesitant due to uncertainty regarding:

  • Interest rates

  • Employment concerns

  • Economic slowdown fears

  • International trade issues

  • Geopolitical instability

TRREB noted that lower home prices and lower borrowing costs have encouraged more buyers to return to the market this spring.

If sales continue rising while inventory continues tightening, market conditions could become more competitive later in 2026.

This matters because real estate markets often shift gradually before sentiment changes more dramatically. Early increases in buyer activity can eventually create stronger competition and firmer pricing if supply does not keep pace.

What This Means for Buyers

Buyers currently remain in a relatively favourable position compared to previous years.

Advantages include:

  • Lower average prices

  • More negotiating power

  • Better property selection

  • Less intense bidding competition in many areas

  • Greater ability to include conditions in offers

However, buyers waiting too long could face increasing competition if market conditions continue tightening throughout spring and summer.

Strategic buyers are focusing on:

  • Proper financing preparation

  • Monitoring inventory closely

  • Acting quickly on well priced properties

  • Targeting motivated sellers

  • Looking at long term value rather than short term fluctuations

What This Means for Sellers

Sellers need to understand that pricing strategy is now more important than ever.

The market is rewarding:

  • Accurate pricing

  • Strong presentation

  • Professional marketing

  • Flexible negotiation

  • Proper timing

Homes that are overpriced often experience:

  • Reduced showings

  • Longer time on market

  • Increased buyer skepticism

  • Larger eventual price reductions

Meanwhile, properties priced properly are still attracting strong interest and, in some cases, multiple offers.

The first one to two weeks after listing remain critical because that is when buyer attention is strongest.

Investor Outlook

Investors continue approaching the market cautiously but selectively.

Some investors remain concerned about:

  • Financing costs

  • Cash flow pressure

  • Condo market softness

  • Economic uncertainty

Others see opportunity in:

  • Reduced competition

  • Lower acquisition prices

  • Long term population growth

  • Immigration driven housing demand

  • Future supply shortages

The long term fundamentals supporting GTA housing demand remain significant, particularly given ongoing population growth and limited housing supply development relative to demand.

Looking Ahead

The more important question now is whether April’s activity marks the beginning of a stronger recovery trend or simply a temporary spring rebound.

Several factors will influence the remainder of 2026:

  • Interest rate direction

  • Employment trends

  • Consumer confidence

  • Trade stability

  • Inflation levels

  • Housing supply trends

If listings continue declining while sales continue rising, market conditions could tighten more noticeably by late 2026.

For now, buyers still maintain meaningful negotiating power in many areas, but sellers with properly priced homes are beginning to see stronger activity compared to earlier months.

The GTA market is showing signs of gradual stabilization, and the next few months will likely provide clearer direction regarding where prices and demand head next.

Source: Toronto Regional Real Estate Board (TRREB), April 2026 Market Report.


📊 Latest Market Insights (Updated Monthly)

✔️ Toronto & GTA Housing Market — March 2026

✔️ Rent vs Own in Toronto (2026): What Happens After 25 Years? A Real Numbers Breakdown!

✔️ Renting vs. Owning: How $2,500/month could cost you $190,000
✔️ GTA Housing — GTA Buyer Guide 2026
✔️ Mississauga Condo Market — Q3 2025
✔️ Durham Region Market Report — Oct 2025
✔️ Bill 60 vs Ontario RTA — What’s Changing?

👉 Read more market reports & analysis →


🏡 Thinking of Buying, Selling, or Investing in the GTA?
Don’t guess—use real data, real listings, and expert guidance.

🔍 Start Exploring Now (Live Search Portals)

👉 Gas Stations for Sale
👉
Commercial & Industrial Properties
👉
Residential Homes Across the GTA
👉
Hotels & Motels – Investment Opportunities
👉
Pre-Construction Condo Projects
👉
Condo Resale Listings (GTA)

📈 Market is shifting—smart investors move early.

📩 Need Clarity Before You Move?

Get straight answers, not sales pressure.

Sami Chowdhury | Broker

Ph: 647-725-0606
📧 samichy@torontobase.com
🌐 torontobased.com | torontobase.ca

Let’s turn market uncertainty into opportunity.

RE/MAX REALTRON REALTY INC, BROKERAGE

209-885 PROGRESS AVE, TORONTO, ON M1H3G3

Ph: 416-289-3333 / Fax: 416-289-4535 


Contact Me, If you are planning to buy, sell, or invest in the GTA, the most important step is understanding where your property or budget fits within these changing conditions.

I can prepare a detailed, data driven breakdown tailored to your situation so you can move forward with clarity and confidence.


Read

Toronto & GTA Housing Market — March 2026

Sales Rising, Prices Adjusting, and Supply Quietly Tightening

The March 2026 housing data for the Greater Toronto Area presents a market that is shifting in a way many buyers and sellers may not fully recognize yet. On the surface, the story looks simple: prices are down compared to last year. But a closer look shows something far more important unfolding beneath that headline.

Sales are rising. New listings are falling. Inventory is tightening. Buyers are active again, but cautious. Sellers are present, but selective. This combination does not describe a declining market. It describes a market in transition.

The more important question is not what happened in March. The more important question is what this shift is setting up for the months ahead.


A Market Moving Out of Correction

March recorded 5,039 home sales across the GTA, an increase of 1.7% compared to March 2025. At the same time, new listings dropped sharply to 14,442, down 16.7% year over year. That divergence between sales and listings is one of the most critical signals in the entire dataset.

During a declining market phase, both sales and prices typically fall together while listings rise. That is not what is happening here.

Instead:

  • Buyers are returning

  • Sellers are holding back

  • Inventory is being absorbed faster than it is being replaced

This is not a collapse. This is a rebalancing phase after a period of price correction.


Prices Are Lower, But That Is Only Part of the Story

The average selling price in March 2026 was $1,017,796, down 6.7% from March 2025. The MLS Home Price Index benchmark declined by 7.4%, confirming that the price adjustment is broad across property types.

For many buyers, this creates a sense of opportunity. Prices are lower than last year, and affordability, while still stretched, has improved relative to peak conditions.

However, price direction alone does not define market conditions.

What matters is how prices interact with:

  • supply

  • demand

  • buyer confidence

  • financing conditions

And in March, those relationships are shifting.


Supply Is Quietly Tightening

While prices are still adjusting downward year over year, supply is moving in the opposite direction.

  • Active listings: 21,596 (down 8% YoY)

  • New listings: down 16.7% YoY

  • Months of inventory: 4.9

At first glance, 21,596 active listings still sounds like a large number. And it is. Buyers still have choice in this market. But the trend matters more than the absolute number.

Fewer new listings means fewer fresh options entering the market. When that happens at the same time that sales are rising, inventory begins to compress.

This is how markets transition.

Not with sudden price spikes, but with tightening conditions that gradually reduce buyer leverage.


Buyer Behaviour Is Still Cautious, But More Active

Even with improving demand, buyers are not rushing.

  • Average sale to list price ratio: 98%

  • Days on market remain elevated compared to last year

  • Buyers are negotiating and comparing options carefully

This tells us that:

  • Buyers are active, but not emotional

  • Decision making is still analytical

  • Competition exists, but is not widespread across all listings

However, behaviour tends to lag behind market structure. Buyers often react to what they see, not what is forming.

Right now, the structure is tightening before buyer urgency fully returns.


Property Type Trends Reveal Where Leverage Exists

Not all segments of the market are behaving the same way. Understanding these differences is critical for both buyers and sellers.

Condo Apartments — The Most Buyer-Favourable Segment

  • Average price: $620,479

  • Active listings: 7,673

  • Days on market: 39

This segment offers:

  • the most inventory

  • the longest selling timelines

  • the most negotiation potential

For first time buyers and investors, this is where flexibility still exists.


Condo Townhouses — The Transitional Option

  • Average price: $739,365

  • Days on market: 36

These properties offer a middle ground between affordability and space. They are often overlooked but can present strong value for buyers looking to move beyond condo apartments.


Freehold Townhomes and Semis — Competitive Balance

  • Townhouse avg price: $931,740

  • Semi detached avg: $1,008,246

  • Days on market: mid 20s range

These segments show stronger demand relative to condos. When priced correctly, they can still move quickly.


Detached Homes — High Value, Selective Demand

  • Average price: $1,342,375

  • Active listings: 9,320

  • Days on market: 28

Detached homes remain the most expensive segment, but they are also showing resilience in demand.

Buyers in this segment tend to be:

  • financially prepared

  • more decisive

  • less sensitive to short term price fluctuations

That keeps this segment relatively stable compared to others.


Interest Rates Are Stabilizing, But Still Matter

The financial environment plays a major role in shaping buyer behaviour.

  • Bank of Canada overnight rate: ~2.3%

  • Prime rate: ~4.5%

  • Mortgage rates:

    • 1 year: 5.49%

    • 3 year: 6.05%

    • 5 year: 6.09%

Rates are not at peak stress levels, but they are still high enough to influence purchasing decisions.

This leads to:

  • more calculated buying decisions

  • stronger focus on affordability

  • increased importance of pre approval

Buyers are not reacting emotionally. They are reacting financially.


What This Means for Buyers

The current market offers a window, but not an unlimited one.

Advantages right now:

  • Prices below last year levels

  • Negotiation still possible

  • Good inventory in certain segments

Constraints emerging:

  • Fewer new listings

  • Gradual increase in demand

  • Potential for tighter conditions ahead

The opportunity is not just about price. It is about timing relative to market direction.


What This Means for Sellers

Sellers are no longer in a declining market, but they are not in a seller driven market either.

This creates a strategic environment.

What works:

  • Accurate pricing from the start

  • Strong presentation and marketing

  • Understanding segment specific demand

What does not work:

  • Overpricing and waiting

  • Relying on past market conditions

  • Assuming buyers will stretch

The market is rewarding preparation and penalizing misalignment.


Investor Perspective — A Positioning Window

For investors, this is not a peak cycle entry point. It is something more subtle.

  • Prices have adjusted

  • Demand is returning

  • Supply is tightening

These are early stage stabilization signals.

Investors who wait for headlines to turn positive often enter after conditions have already shifted. The current market requires a forward looking approach.

The focus should be on:

  • long term fundamentals

  • cash flow sensitivity to rates

  • segment selection

Condo apartments and entry level segments may offer the most flexibility, but each strategy depends on individual positioning.


Risk Scenarios to Watch

No market shift is without risk. There are several scenarios that could influence direction.

1. Supply Remains Constrained

If new listings continue to decline, competition could increase faster than expected.

2. Demand Accelerates

If buyer confidence improves due to stable rates or economic signals, absorption could tighten quickly.

3. Rates Shift Unexpectedly

Even small changes in borrowing costs can influence affordability and sentiment.

4. Seller Behaviour Changes

If more sellers enter the market suddenly, supply could rebalance again.


What Comes Next

The March data does not signal a surge. It signals a turning point.

The combination of:

  • rising sales

  • declining listings

  • stabilizing prices

suggests that the market is moving toward equilibrium.

The next phase depends heavily on supply.

If listing volume remains low, the balance could shift toward sellers faster than expected. If supply increases, the current conditions could persist longer.

Either way, the direction is no longer downward.


Final Strategic Takeaway

This is a market where positioning matters more than prediction.

Buyers should focus on:

  • securing value while negotiation exists

  • acting when the right property appears

  • preparing financially before entering

Sellers should focus on:

  • pricing correctly from day one

  • aligning with current market conditions

  • executing with strong marketing strategy

Investors should focus on:

  • identifying segments with flexibility

  • planning for long term stability

  • entering before sentiment shifts


🏡 Thinking of Buying, Selling, or Investing in the GTA?
Don’t guess—use real data, real listings, and expert guidance.

🔍 Start Exploring Now (Live Search Portals)

👉 Gas Stations for Sale
👉
Commercial & Industrial Properties
👉
Residential Homes Across the GTA
👉
Hotels & Motels – Investment Opportunities
👉
Pre-Construction Condo Projects
👉
Condo Resale Listings (GTA)

📈 Market is shifting—smart investors move early.


📊 Latest Market Insights (Updated Monthly)

✔️ Rent vs Own in Toronto (2026): What Happens After 25 Years? A Real Numbers Breakdown!

✔️ Renting vs. Owning: How $2,500/month could cost you $190,000
✔️ GTA Housing —
GTA Buyer Guide 2026
✔️ Mississauga Condo Market —
Q3 2025
✔️ Durham Region Market Report —
Oct 2025
✔️ Bill 60 vs Ontario RTA —
What’s Changing?

👉 Read more market reports & analysis →


📩 Need Clarity Before You Move?

Get straight answers, not sales pressure.

Sami Chowdhury | Broker
📧
samichy@torontobase.com
🌐
torontobased.com | torontobase.ca

Let’s turn market uncertainty into opportunity.


Contact Me, If you are planning to buy, sell, or invest in the GTA, the most important step is understanding where your property or budget fits within these changing conditions.

I can prepare a detailed, data driven breakdown tailored to your situation so you can move forward with clarity and confidence.


Read

🏛️ Ontario’s New HST Rebate Could Save Buyers $130K — But Will It Actually Make Homes More Affordable?

 📌 Introduction: Why This Policy Matters Right Now

Ontario’s housing market is at a critical turning point.

After years of:

  • skyrocketing prices

  • aggressive interest rate hikes

  • collapsing affordability

…we are now seeing something different:

👉 inventory rising
👉 buyers hesitating
👉 pre-construction slowing dramatically

And into this fragile environment, the Ontario government has introduced one of the most aggressive housing tax interventions in recent history:

💥 A temporary removal of the full 13% HST on new homes

This is not a minor tweak.

This is a massive demand-side stimulus designed to:

  • revive construction

  • boost buyer confidence

  • protect the economy

But here’s the real question:

👉 Will this actually make housing more affordable… or just push prices higher again?

Let’s break it down.


🧾 What Exactly Changed? (Policy Breakdown)

The new proposal expands the GST/HST New Housing Rebate dramatically.

🏠 Key Highlights:

✔ Full 13% HST rebate on new homes
✔ Applies to homes up to $1 million (max ~$130,000 savings)
✔ Maintains rebate up to $1.5 million
✔ Gradual phase-out to ~$1.85M+
✔ Valid for:

  • primary residences

  • rental housing (separate rebate stream)

✔ Timeline:
📅 April 1, 2026 → March 31, 2027

✔ Federal + Provincial partnership:

  • Federal covers ~5% GST

  • Ontario covers 8% portion


🧠 How the Rebate Actually Works (Most People Misunderstand This)

This is where many buyers get confused.

❌ It is NOT:

  • a direct price drop

  • a builder discount

  • free money at signing

✅ It IS:

  • a tax rebate mechanism

Meaning:

  • You either:

    • get credited by the builder

    • or claim it after closing

👉 The price of the home itself does NOT automatically decrease

This distinction is critical — and will shape the entire market impact.


🕰️ Historical Context: Why This Policy Exists

To understand this move, we need to look at what happened over the last 3–4 years.

📉 What Went Wrong in the Market:

  1. Interest rates surged (2022–2024)

  2. Pre-construction demand collapsed

  3. Developers paused projects

  4. Housing starts declined

  5. Supply pipeline weakened

Ontario is now facing a serious problem:

👉 Not enough homes being built for future demand

This policy is designed to fix that — fast.


👥 Who Benefits the Most?

Let’s break this down by group:


🧑‍💼 1. First-Time Buyers

Biggest winners on paper.

💰 Example:

  • $900,000 new condo

  • HST = ~$117,000

👉 That could now be rebated

Impact:
✔ easier entry
✔ lower upfront cost
✔ psychological boost to buying


🏠 2. Move-Up Buyers

Also benefit — especially in:

  • $900K–$1.5M range

👉 This is HUGE in GTA suburbs:

  • Milton

  • Pickering

  • Oshawa

  • Brampton


🏢 3. Investors (Important)

This is where things get interesting.

✔ Rental rebate still applies
✔ Lower cost → higher ROI

👉 Expect:

  • investor re-entry into pre-construction


🧱 4. Developers (BIGGEST BENEFICIARIES)

Let’s be honest:

👉 Developers may benefit the most

Why?

Because:

  • demand increases

  • pricing power increases

  • inventory absorption improves


📊 Economic Impact (Macro View)

Ontario estimates:

✔ +8,000 housing starts
✔ +21,000 jobs
✔ +$2.7B GDP


🧠 What This Means:

This policy is not just about housing.

👉 It is an economic stimulus package

Housing drives:

  • construction jobs

  • materials demand

  • banking activity

  • municipal revenue


🏘️ REAL ESTATE IMPACT (DEEP ANALYSIS — THIS IS THE CORE)

Now let’s get into the expert-level breakdown.


🔥 1. Pre-Construction Market Will Surge First

This is where the biggest impact will happen.

Why?

✔ HST applies mainly to NEW builds
✔ resale homes don’t benefit

👉 Result:

📈 Pre-con demand increases
📈 Builder confidence improves
📈 Projects restart


⚠️ 2. Developers May Capture the Rebate (CRITICAL RISK)

This is the #1 issue most people ignore.

If demand increases rapidly:

👉 Developers may raise prices

Example:

Before:

  • Unit price: $900K

  • HST rebate: minimal

After:

  • Unit price: $950K–$980K

  • Buyer “still feels savings”

👉 The benefit gets partially absorbed by developers


⚖️ 3. Supply vs Demand Timing Problem

Demand:

  • Immediate

Supply:

  • Takes years

👉 This creates a short-term imbalance

Result:
📈 Prices may rise before supply catches up


🏚️ 4. Resale Market Gets Left Behind

This is critical for your business.

👉 Resale homes:

  • DO NOT benefit from rebate

Impact:

  • Buyers shift to new builds

  • Resale demand softens temporarily

BUT…

Later:

  • spillover effect returns


📉 5. Short-Term vs Long-Term Price Effects

Short-Term:

  • Demand spike

  • Price pressure upward

Medium-Term:

  • More supply enters pipeline

Long-Term:

  • Stabilization (IF supply actually increases)


🧠 6. Investor Behavior Will Change

Expect:

✔ More assignment activity
✔ More pre-con flips
✔ Rental inventory growth


⚠️ RISKS & UNINTENDED CONSEQUENCES


🚨 1. Price Inflation Risk

Biggest concern.

👉 Policy may:

  • increase affordability temporarily

  • but raise prices structurally


🚨 2. Developer Margin Capture

Instead of buyers saving:

👉 developers increase margins


🚨 3. Policy Cliff (VERY IMPORTANT)

Ends March 2027.

👉 What happens after?

  • demand drops suddenly

  • market shock possible


🚨 4. Regional Inequality

GTA benefits more than:

  • rural Ontario

  • smaller markets


🔮 Forward Outlook (GTA Strategy Insight)

Here’s what smart buyers and sellers should watch:


🧠 Buyers:

  • Early movers benefit most

  • Waiting = higher prices risk


🧠 Sellers:

  • Temporary slowdown possible

  • Then rebound


🧠 Investors:

  • Pre-con window reopening


🧾 Final Verdict

This policy is powerful.

But it is NOT a magic solution.

👉 It will:
✔ stimulate construction
✔ boost confidence
✔ help some buyers

But also:

⚠️ risk pushing prices higher
⚠️ benefit developers heavily


📌 BOTTOM LINE

👉 This is a market-moving policy, not just a rebate.

And if you understand it early…

👉 you can position yourself ahead of 90% of buyers and sellers.Sources: 

Sources:

GST/HST New Housing Rebate

Ontario Expanding HST Rebate to Lower the Cost of New Homes in Partnership with the Federal Government


🏡 Thinking of Buying, Selling, or Investing in the GTA?
Don’t guess—use real data, real listings, and expert guidance.

🔍 Start Exploring Now (Live Search Portals)

👉 Gas Stations for Sale
👉
Commercial & Industrial Properties
👉
Residential Homes Across the GTA
👉
Hotels & Motels – Investment Opportunities
👉
Pre-Construction Condo Projects
👉
Condo Resale Listings (GTA)

📈 Market is shifting—smart investors move early.


📊 Latest Market Insights (Updated Monthly)

✔️ Rent vs Own in Toronto (2026): What Happens After 25 Years? A Real Numbers Breakdown!

✔️ Renting vs. Owning: How $2,500/month could cost you $190,000
✔️ GTA Housing — GTA Buyer Guide 2026
✔️ Mississauga Condo Market — Q3 2025
✔️ Durham Region Market Report — Oct 2025
✔️ Bill 60 vs Ontario RTA — What’s Changing?

👉 Read more market reports & analysis →


📩 Need Clarity Before You Move?

Get straight answers, not sales pressure.

Sami Chowdhury | Broker
📧 samichy@torontobase.com
🌐 torontobased.com | torontobase.ca

Let’s turn market uncertainty into opportunity.


Read

Rent vs Own in Toronto (2026): What Happens After 25 Years? A Real Numbers Breakdown

Introduction: The $2,800 Question Every Renter Is Asking

If you’re paying around $2,500–$3,000/month in rent in Toronto, you’re not alone.

But here’s the real question more people are asking in 2026:

👉 “What if that same monthly payment could go toward owning a home?”

With interest rates stabilizing and more inventory coming into the market, the conversation has shifted from:

❌ Rent vs Home Price
✅ Rent vs Monthly Ownership Cost

Let’s break this down using a real scenario — and more importantly, what it looks like 25 years later.


The Scenario: Renting vs Owning

Buying Scenario

  • Purchase Price: $630,000

  • Down Payment: $50,000

  • Mortgage: $580,000

  • Interest Rate: 3.5%

  • Amortization: 25 years

  • Monthly Payment: $2,895.77

Renting Scenario

  • Monthly Rent: $2,800

  • Annual Increase (conservative): 3%


Monthly Reality: Almost the Same Cost

At first glance:

  • Rent = $2,800/month

  • Mortgage = $2,896/month

👉 Difference: ~$96/month

That’s the biggest mindset shift in today’s market:

💡 You’re not comparing affordability anymore
You’re comparing where your money goes


Where Your Money Goes

Renting

  • 100% of your payment = expense

  • No ownership

  • No long-term return

Owning

Each payment is split into:

  • Interest (cost)

  • Principal (your equity)

👉 Over time, more of your payment goes toward ownership, not cost.


After 25 Years: The Big Difference

If You Buy

After 25 years:

✔ Mortgage is fully paid off
✔ You own the property 100%

Now let’s estimate value:

Conservative Appreciation (3% annually)

Future Value of $630,000 after 25 years:

👉 ≈ $1,320,000 – $1,400,000

So your net worth from this property alone:

💰 ~$1.3M+ in equity


If You Rent

Let’s calculate total rent paid:

Year 1: $2,800/month
With 3% annual increase over 25 years:

👉 Total rent paid ≈ $1,150,000 – $1,250,000

And after 25 years:

❌ You own nothing
❌ No equity
❌ Still paying rent (likely much higher)


Side-by-Side Comparison After 25 Years

Scenario

Total Paid

What You Own

Buy

~$918,730 (mortgage payments)

~$1.3M+ property

Rent

~$1.2M+ (rent paid)

$0

👉 Difference in net worth: ~$1.3M+


The Hidden Advantage of Ownership

Beyond just numbers:

✔ Inflation Protection

Your mortgage stays relatively stable
Rent keeps rising

✔ Forced Savings

Every payment builds equity

✔ Leverage

You control a $630K asset with $50K down

✔ Future Flexibility

• Sell and upgrade
• Refinance
• Rent it out


But Let’s Be Real: Ownership Isn’t for Everyone

Challenges of Buying

  • Need down payment + closing costs

  • Must qualify for mortgage

  • Responsible for maintenance

  • Less flexibility to move

When Renting Makes Sense

  • Short-term plans

  • Uncertain income

  • Not ready for responsibility


Why 2026 Is a Turning Point

The GTA market is shifting:

• Prices stabilized in many segments
• Inventory increased
• Buyers have more negotiating power
• Interest rates more predictable

👉 This creates a window of opportunity for renters to enter the market.


Key Takeaway

If you’re paying around $2,800/month in rent, you may already be:

👉 Financially capable of owning

And the long-term difference is massive:

💡 Rent = expense
💡 Ownership = wealth building


Final Thought

The question is no longer:

❌ “Can I afford to buy?”

It’s:

✅ “Can I afford not to own over the next 25 years?”


🏡 Thinking of Buying, Selling, or Investing in the GTA?
Don’t guess—use real data, real listings, and expert guidance.

🔍 Start Exploring Now (Live Search Portals)

👉 Gas Stations for Sale
👉
Commercial & Industrial Properties
👉
Residential Homes Across the GTA
👉
Hotels & Motels – Investment Opportunities
👉
Pre-Construction Condo Projects
👉
Condo Resale Listings (GTA)

📈 Market is shifting—smart investors move early.


📊 Latest Market Insights (Updated Monthly)

✔️ Renting vs. Owning: How $2,500/month could cost you $190,000
✔️ GTA Housing — GTA Buyer Guide 2026
✔️ Mississauga Condo Market — Q3 2025
✔️ Durham Region Market Report — Oct 2025
✔️ Bill 60 vs Ontario RTA — What’s Changing?

👉 Read more market reports & analysis →


📩 Need Clarity Before You Move?

Get straight answers, not sales pressure.

Sami Chowdhury | Broker
📧 samichy@torontobase.com
🌐 torontobased.com | torontobase.ca

Let’s turn market uncertainty into opportunity.


Read

Toronto Housing Market February 2026: Prices Drop But Supply Tightens

 February 2026 GTA Housing Market Overview

The February 2026 housing statistics for the Greater Toronto Area reveal a market that continues to adjust following the rapid price growth and interest-rate changes of the past several years. While home prices declined compared with the same time last year, the supply of homes entering the market dropped even more sharply. This dynamic has begun to tighten overall market conditions, even though buyers still retain some negotiating leverage.

According to the February 2026 market data, 3,868 residential properties were sold across the GTA during the month. This represents a 6.3 percent decrease compared with February 2025. Despite the drop in transactions, the supply of new homes entering the market fell much more dramatically.

New listings declined to 10,705 properties, representing a 17.7 percent year-over-year decrease. When listing supply falls faster than demand, the market often begins to tighten. This is exactly what the February numbers suggest.

Although fewer homes were sold compared with last year, the reduction in new listings means that the overall level of inventory did not increase significantly.

Inventory Levels Across the GTA

At the end of February 2026, there were 19,314 active listings across the GTA housing market. This represents a 2.4 percent decline compared with the same month in 2025.

When comparing active listings with the number of homes sold during the month, the market had approximately five months of inventory. In real estate analysis, this level is generally considered a balanced market, though it still leans slightly in favor of buyers.

During the intense seller’s market conditions of previous years, inventory levels were significantly lower. The current level of supply indicates that buyers now have more options and more time to evaluate properties before making purchasing decisions.

However, the sharp drop in new listings could gradually shift the balance of the market if this trend continues.

GTA Home Prices Continue to Adjust

The average selling price across all home types in the GTA during February 2026 was $1,008,968. This represents a 7.1 percent decrease compared with February 2025.

Another key measure of home values is the MLS Home Price Index benchmark price, which attempts to measure the value of a typical home by controlling for differences in the mix of properties sold. The benchmark price across the GTA reached $938,800 in February 2026, representing a 7.89 percent year-over-year decline.

The fact that both the average price and benchmark price declined confirms that the price adjustment is not simply due to more lower-priced homes being sold. Instead, home values across many property categories have softened compared with last year.

Detached Homes Continue to Lead the Market

Detached homes remain the dominant segment of the GTA housing market. In February 2026, 1,683 detached properties were sold, representing the largest share of total transactions.

The average price of a detached home reached $1,325,654.

Other property types recorded the following average prices:

• Semi-detached homes: $1,027,376
• Freehold townhouses: $930,779
• Condo townhouses: $748,500
• Condo apartments: $626,650

These numbers illustrate the continued affordability gap between property types. While detached homes remain the most desirable housing option for many buyers, the price difference often pushes buyers toward townhouses and condominium units.

Condo Market Shows Larger Price Declines

The condominium sector has experienced the most noticeable price pressure over the past year.

The benchmark price for condominium apartments across the GTA declined approximately 9.5 percent year-over-year, making it the segment most affected by recent market adjustments.

Despite the price declines, condo apartments remain an essential entry point for first-time buyers and investors. With an average price of $626,650, condos offer a more accessible option compared with detached homes and freehold properties.

Regional Differences Across the GTA

Housing market conditions vary significantly across the different regions of the Greater Toronto Area.

Toronto

The City of Toronto recorded 1,491 home sales in February 2026, with an average price of $1,019,144. Inventory levels in the city remained close to the overall GTA average.

York Region

York Region recorded 683 transactions, with an average home price of $1,133,471. This region continues to attract buyers looking for larger suburban homes.

Peel Region

Peel Region reported 706 sales, with an average price of $933,616. Peel continues to offer relatively more affordable housing compared with Toronto and York.

Durham Region

Durham recorded 454 sales, with an average price of $850,304. Durham also had the tightest supply conditions, with approximately 3.5 months of inventory, indicating stronger demand relative to supply.

Market Conditions: Balanced but Buyer-Friendly

The February numbers suggest that the GTA housing market remains balanced but still slightly favorable to buyers.

The average sale-to-list price ratio was approximately 97 percent, meaning homes typically sold slightly below their asking price.

Additionally, homes required more time to sell compared with the previous year. The average listing days on market reached 36 days, while the average property days on market reached 54 days.

These longer selling times reflect a market where buyers have more time to negotiate and compare properties.

Outlook for the GTA Housing Market

Looking forward, the most important factor to monitor will likely be the relationship between supply and demand.

If the trend of declining new listings continues while buyer demand stabilizes or increases, the market could gradually tighten later in the year. On the other hand, if economic conditions weaken or borrowing costs rise further, price pressure could persist.

For now, the February 2026 numbers show a market that remains in transition, balancing lower prices with declining supply levels.


🏡 Thinking of Buying, Selling, or Investing in the GTA?
Don’t guess—use real data, real listings, and expert guidance.

🔍 Start Exploring Now (Live Search Portals)

👉 Gas Stations for Sale
👉
Commercial & Industrial Properties
👉
Residential Homes Across the GTA
👉
Hotels & Motels – Investment Opportunities
👉
Pre-Construction Condo Projects
👉
Condo Resale Listings (GTA)

📈 Market is shifting—smart investors move early.


📊 Latest Market Insights (Updated Monthly)

✔️ Renting vs. Owning: How $2,500/month could cost you $190,000
✔️ GTA Housing — GTA Buyer Guide 2026
✔️ Mississauga Condo Market — Q3 2025
✔️ Durham Region Market Report — Oct 2025
✔️ Bill 60 vs Ontario RTA — What’s Changing?

👉 Read more market reports & analysis →


📩 Need Clarity Before You Move?

Get straight answers, not sales pressure.

Sami Chowdhury | Broker
📧 samichy@torontobase.com
🌐 torontobased.com | torontobase.ca

Let’s turn market uncertainty into opportunity.


Read

GTA Housing Market Report – February 2026

Sales Decline Slightly While Listings Drop Sharply Across the Greater Toronto Area

The Greater Toronto Area housing market in February 2026 continued to reflect the complex transition period that began in late 2024. While home sales remained below levels seen a year ago, the supply of new listings fell even faster. This shift in market dynamics is gradually tightening overall market conditions, although prices are still under pressure compared to last year.

According to the February 2026 market statistics, there were 3,868 residential transactions recorded across the GTA, representing a 6.3 percent decline compared to February 2025. Despite this decrease in sales activity, the market experienced a significantly larger drop in new listings, which fell 17.7 percent year-over-year to 10,705 properties.

This imbalance between sales and new listings has important implications for the market. While buyers still enjoy considerable choice compared to the pandemic-era boom years, the pace at which new supply is entering the market has slowed noticeably. As a result, overall inventory levels declined slightly compared to last year.

Active listings at the end of February totaled 19,314 homes, down 2.4 percent from the same time last year. With sales activity at current levels, this represents approximately five months of inventory, which is generally considered a balanced market leaning slightly toward buyers.


Home Prices Continue to Ease

Home prices in the GTA continued to show downward pressure compared to the previous year. The average selling price across all home types in February 2026 was $1,008,968, which represents a 7.1 percent decline year-over-year.

Similarly, the MLS Home Price Index benchmark price, which measures price trends while controlling for changes in the mix of homes sold, also showed a decline. The composite benchmark price reached $938,800 in February, representing a 7.89 percent decrease compared to February 2025.

The decline in benchmark prices confirms that the price changes are not simply the result of more lower-priced homes selling. Instead, it reflects a broader adjustment in home values across the market.

Despite these year-over-year declines, prices have remained relatively stable compared to late 2025 levels, suggesting that the market may be approaching a stabilization phase after the volatility experienced during the interest-rate tightening cycle.


Detached Homes Remain the Largest Segment of the Market

Detached homes continued to represent the largest share of transactions across the GTA housing market.

In February 2026:

  • Detached homes recorded 1,683 sales, with an average price of $1,325,654

  • Semi-detached homes recorded 336 sales, averaging $1,027,376

  • Freehold townhouses recorded 369 sales, averaging $930,779

  • Condominium townhouses recorded 329 sales, averaging $748,500

  • Condominium apartments recorded 1,088 sales, with an average price of $626,650

Detached homes remain the most sought-after property type, particularly among move-up buyers and families seeking larger living spaces. However, affordability challenges continue to push many buyers toward townhouses and condominium units.

The condominium apartment market, in particular, continues to play a critical role in maintaining transaction volume, representing the second-largest category of sales across the region.


Condo Market Under Pressure

The condominium sector has experienced some of the most noticeable price declines in the GTA market over the past year.

Benchmark data shows that apartment-style condominium prices fell approximately 9.5 percent year-over-year, making this segment one of the most impacted by the broader housing correction.

Several factors are contributing to the weakness in the condo market:

• Higher interest rates reducing investor demand
• Increased new condominium supply entering the market
• Higher carrying costs for investment properties
• Slower population growth compared to the immediate post-pandemic rebound

However, condos remain an essential entry point for first-time buyers, and affordability improvements could eventually bring more buyers back into this segment.


Regional Market Breakdown

Market conditions varied across the different regions within the Greater Toronto Area.

Toronto

The City of Toronto recorded 1,491 sales in February, with an average price of $1,019,144. Inventory levels were relatively balanced, with approximately five months of supply.

York Region

York Region recorded 683 sales, with an average price of $1,133,471. Inventory levels were slightly higher than Toronto, suggesting somewhat softer conditions.

Peel Region

Peel Region saw 706 transactions, with an average price of $933,616. The region continues to attract buyers seeking more affordable options relative to Toronto.

Durham Region

Durham recorded 454 sales, with an average price of $850,304. Interestingly, Durham had the lowest inventory levels among major regions, with roughly 3.5 months of supply, indicating comparatively tighter market conditions.

These regional differences reflect variations in affordability, commuting patterns, and local housing supply.


Market Balance: Buyers Still Hold Some Advantage

With five months of inventory across the GTA, the market remains relatively balanced, although buyers continue to maintain some negotiating leverage.

The average sale-to-list price ratio was approximately 97 percent, indicating that most properties are selling slightly below asking price.

Additionally, homes are taking longer to sell compared to the previous year. The average listing days on market reached 36 days, while the average property days on market reached 54 days.

These longer selling times highlight the more cautious behavior of buyers, who now have more time to evaluate properties and negotiate prices.


What This Means for Buyers

For buyers, the February 2026 market offers several advantages compared to the highly competitive markets of recent years.

Buyers currently benefit from:

• Increased property selection
• More time to evaluate options
• Greater negotiating power
• Reduced bidding competition

However, affordability remains a challenge, particularly for detached homes and larger properties. Mortgage rates, income growth, and economic confidence will continue to play important roles in determining buyer activity through the remainder of the year.


What This Means for Sellers

For sellers, realistic pricing and strategic marketing are now more important than ever.

In today’s market:

• Overpriced homes tend to remain on the market longer
• Well-priced properties still attract strong interest
• Professional marketing can significantly improve results
• Pricing strategy often determines whether a home sells quickly or sits on the market

Sellers who understand current market conditions and price their homes competitively can still achieve successful outcomes.


Outlook for the GTA Housing Market

Looking ahead, several factors will shape the direction of the GTA housing market in 2026.

Key influences include:

• Interest rate policy from the Bank of Canada
• Population growth and immigration levels
• New housing supply entering the market
• Employment and economic conditions
• Consumer confidence among buyers

If listing supply remains limited while demand stabilizes, the market could gradually move toward tighter conditions later in the year. However, any significant changes in borrowing costs or economic conditions could alter that trajectory.

For now, the February data suggests that the GTA housing market remains in a period of adjustment, balancing slower sales activity with declining supply levels.


About the Author

Sami Chowdhury
Broker

RE/MAX Realtron Realty Inc., Brokerage
885 Progress Ave, Suite 209
Toronto, ON M1H 3G3

📞 Direct: 647-725-0606
☎ Office: 416-289-3333
✉ Email:
samichy@torontobase.com

🌐 www.TorontoBase.com

GTA Property Search • Market Updates • New Listings


Follow Me

LinkedIn | Facebook | Instagram | X(Former Twitter)  | YouTube | Snapchat


Read

Why Reading Books and Newspapers — Online or in Print — Is Still Absolutely Necessary

In an era defined by short videos, scrolling headlines, and algorithm-driven feeds, reading books and newspapers may seem less urgent than it once was. Yet the evidence is clear: sustained reading — whether in print or digital format — remains essential for personal development, informed citizenship, and long-term cognitive health.

This article explains why reading remains necessary, what has changed in the digital age, who is affected, and what it means for everyday life in Canada.


📘 What Is Happening

Over the past 20 years, reading habits have shifted dramatically.

• Print newspaper circulation has declined
• Book reading competes with streaming and social media
• Many Canadians now consume news primarily through short-form content

At the same time, literacy research shows a growing divide between deep reading and surface scanning. Digital platforms encourage rapid consumption, while books and structured journalism require sustained attention.

This shift has created concern among educators, policy experts, and public institutions. The core issue is not whether information is available — it is whether people are engaging with it deeply enough to understand complex topics.

Reading books and reputable newspapers remains one of the most reliable ways to build comprehension, critical thinking, and informed judgement.


📰 Why This Change Exists

Several structural changes explain the shift away from traditional reading:

1. Digital Convenience

News is now instantly accessible through phones. Alerts and headlines replace full articles. Convenience reduces friction — but also depth.

2. Algorithmic Personalization

Social media platforms prioritize engagement. Content is selected based on past behaviour, not necessarily quality or balance. This can narrow exposure to diverse viewpoints.

3. Attention Economy Pressures

Modern media competes for attention. Short content is easier to consume, but long-form reading builds stronger comprehension.

4. Declining Print Infrastructure

Local newspapers across Canada have closed or consolidated, reducing community-based reporting.

None of these shifts eliminate the importance of reading. They simply change how and where it happens.


📚 What Changed From Before

Historically:

• Newspapers were primary sources of civic information
• Books were central to formal education
• Reading required deliberate effort

Today:

• News often arrives through feeds rather than front pages
• Articles are skimmed rather than studied
• Opinions can circulate faster than verified reporting

The difference is not access to information — it is depth of engagement.

Books provide context and nuance. Newspapers provide verified reporting, editorial standards, and accountability. Short posts often provide reaction without explanation.


👥 Who Is Affected and How

Students

Reading builds vocabulary, analytical skills, and long-term comprehension. Educational outcomes are strongly linked to sustained reading habits.

Working Professionals

Policy changes, economic shifts, and industry trends require deeper understanding than headlines provide. Reading credible sources improves decision-making.

Homeowners and Voters

Municipal policies, interest rates, infrastructure projects, and regulatory changes directly affect property values and household finances. Understanding these topics requires more than summaries.

Seniors

Regular reading supports cognitive health and memory retention.

Communities

Local journalism holds institutions accountable. Without readers, accountability weakens.


🔎 Common Misunderstandings Clarified

“Everything is online, so books are outdated.”

Digital access does not replace structured knowledge. Books provide depth and sustained argument that fragmented content cannot replicate.

“Social media keeps me informed.”

Social feeds often amplify popular or emotional content, not necessarily accurate reporting.

“Reading takes too much time.”

Reading 20–30 minutes per day significantly improves comprehension and knowledge over time.

“Short summaries are enough.”

Summaries provide conclusions. Reading provides understanding.


🏠 What This Means in Real Life

Reading affects everyday decisions in practical ways:

• Understanding mortgage rate changes
• Interpreting government housing policy
• Evaluating economic forecasts
• Identifying misinformation
• Making informed voting decisions

When individuals rely only on fragmented information, decisions may be based on incomplete context.

Books develop long-term thinking. Newspapers provide verified current context. Together, they strengthen informed citizenship.


📈 The Cognitive and Social Benefits of Reading

Research consistently shows that sustained reading:

• Improves concentration
• Expands vocabulary
• Enhances empathy
• Strengthens analytical thinking
• Reduces stress

In contrast, constant short-form content consumption can reduce attention span over time.

The issue is not technology itself — it is balance. Digital reading is beneficial when it involves full articles, investigative reporting, and long-form journalism.


🧭 What to Watch Next

Several trends will shape reading habits in Canada:

• Growth of digital subscriptions to reputable newspapers
• Increased focus on media literacy education
• Expansion of audiobooks and e-readers
• Public library modernization
• Policy discussions around supporting local journalism

Citizens who actively choose credible sources will remain better equipped to navigate change.


🔑 Strong Takeaway

Reading books and newspapers — online or in print — is not a nostalgic habit. It is a foundational skill for informed decision-making in a complex society.

In a world saturated with information, depth matters more than speed. Sustained reading builds clarity, context, and resilience against misinformation.

The format may evolve. The necessity does not.


Sami Chowdhury

Sami Chowdhury is a licensed real estate broker in Ontario serving the Greater Toronto Area. He focuses on data-driven insights, clarity, and client education to help individuals understand housing, policy, and economic trends. His work emphasizes informed decision-making over speculation, and long-term understanding over short-term reaction.

Sami Chowdhury, Broker
RE/MAX Realtron Realty Inc.
Serving the Greater Toronto Area
www.torontobased.com
www.torontobase.ca

Read
This website may only be used by consumers that have a bona fide interest in the purchase, sale, or lease of real estate of the type being offered via the website. The data relating to real estate on this website comes in part from the MLS® Reciprocity program of the PropTx MLS®. The data is deemed reliable but is not guaranteed to be accurate.